PART 1 TITLE: The Night My Father Threw Me Out, He Had No Idea How Much of His Comfortable Life Belonged to Me
My suitcase struck the marble steps with a hard, hollow sound, bounced against the banister, and came to rest near the front door. One wheel broke off and rolled beneath a cabinet. I watched it disappear while my father stood at the top of the staircase, breathing heavily, his face flushed with anger. He had just told me to leave his house and never return. Then he added that he no longer considered me his daughter. I was thirty-four years old, and the strangest part was that I still wanted him to take it back.
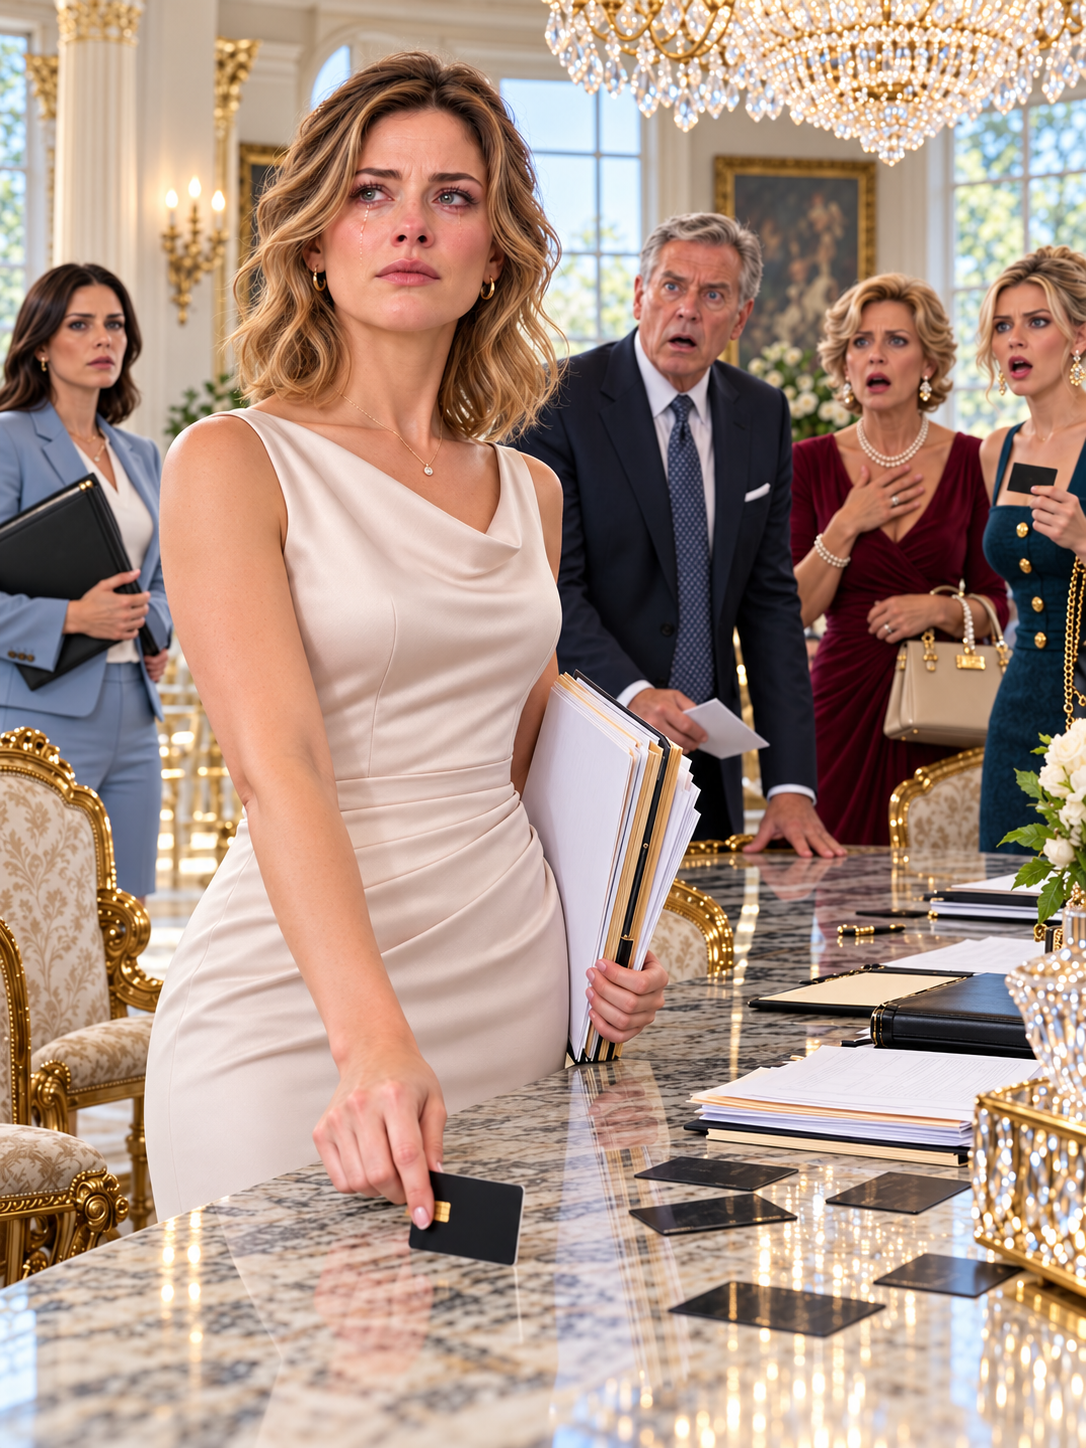
My mother stood beside him, one hand gripping the handle of a designer handbag. The leather was pale cream, the hardware polished gold. I recognized it immediately because I had seen the charge for twelve thousand dollars appear on my credit card statement three weeks earlier. At the time, my mother had described the purchase as something necessary for the household. I had been too busy dealing with a difficult client deadline to question her. Seeing the bag tucked against her hip while my father ordered me out made that explanation seem particularly insulting.
I bent down to retrieve my suitcase. Before I could straighten, my younger sister, Madison, appeared on the landing. She had been watching the argument from her bedroom doorway, offering occasional comments whenever my father needed encouragement. Now she leaned over the railing and called down to me. “Emily, before you go, leave the credit card on the hall table. Mom and I have appointments at the boutiques tomorrow.” Her voice carried the mild impatience of someone reminding a roommate to replace the milk.
I looked up at her. Madison was twenty-eight, beautifully dressed, and apparently untouched by the absurdity of what she had just said. My father had disowned me less than a minute earlier. My mother was holding a handbag purchased with my money. And my sister was concerned about whether her shopping plans would be inconvenienced. I asked Madison to repeat herself. She frowned, as though my hearing had suddenly become another burden the family was expected to tolerate.
“Don’t make everything difficult,” she said. “You know Mom keeps the household card. Just leave it here.” My father gave a short, contemptuous laugh. He told me that whatever happened between us, I still had responsibilities toward the people who had raised me. The statement might have sounded reasonable to a stranger. Standing in that foyer, however, I knew exactly what those responsibilities had become. I was expected to provide the money, accept the criticism, and remain grateful whenever anyone allowed me to participate in family decisions.
I had spent seven years living under that arrangement. When my father’s construction company came close to bankruptcy, I paid outstanding suppliers and helped settle several urgent debts. When my mother insisted she needed a luxury SUV because her older car was becoming unreliable, I arranged the financing and made the monthly payments. When Madison wanted an expensive apartment, new clothes, vacations, and help with her bills, I found myself covering those expenses as well. Every request arrived wrapped in the language of family loyalty. Refusing one was treated as a personal betrayal.
My name is Emily Bennett. I work in financial consulting, helping businesses understand where their money goes and how to keep operating when their expenses threaten to overwhelm them. I earned my position through years of difficult projects, long evenings, and weekends spent studying while my friends went out. I was proud of my work, although I rarely discussed the details with my family. My father considered my profession a comfortable office job. Madison called it moving numbers around. Neither seemed curious about the amount of effort required to earn the money they spent.
I had come to my parents’ house that Friday intending to discuss our finances, not end our relationship. Earlier in the week, I had discovered several unusually large charges on an account my mother used. I wanted to understand what had happened before deciding whether the arrangement could continue. I brought printed statements, a notebook, and a simple proposal for reducing the family’s dependence on me. My suitcase was there because my mother had asked me to stay through Sunday. She had sounded unusually affectionate on the telephone, which should probably have warned me that she wanted something.
Dinner began pleasantly enough. My father talked about a construction contract he hoped to win. Madison described a resort she wanted to visit. My mother asked whether I would be available the following week to accompany her to a dealership. I listened, passing the potatoes, until I realized they were discussing new expenses without once mentioning how they would be paid. When I suggested postponing the dealership appointment, my mother stopped eating. Madison rolled her eyes. My father asked why I had come to dinner if all I intended to do was criticize everyone.
I placed the statements beside my plate and explained that my monthly contributions had become unsustainable. I could continue helping with genuine necessities for a limited period, but I was no longer willing to finance expensive personal purchases. I had barely finished speaking when Madison accused me of humiliating our mother. My father told me I was exaggerating the situation. My mother said very little. She carefully closed her handbag, placed it beside her chair, and watched me as though she were measuring how serious I intended to be.
Then I mentioned the twelve-thousand-dollar purchase. My mother touched the handbag immediately. She said it had been on sale and that she deserved something beautiful after all the sacrifices she had made raising two daughters. Madison agreed, adding that successful people did not usually embarrass their parents by discussing money at the dinner table. I pointed out that I had never authorized the purchase. My father pushed back his chair so abruptly that it scraped the floor. He demanded to know whether I was accusing my mother of stealing.
I told him I was asking why an unauthorized luxury purchase had appeared on my account. The distinction mattered to me. Apparently, it did not matter to him. He reminded me that I had lived in his house as a child, eaten food he purchased, and attended schools he helped pay for. He spoke as if those ordinary responsibilities of parenthood had created a permanent financial obligation. I said that I appreciated the care I had received growing up, but that gratitude did not mean surrendering control of my finances.
That was when his temper broke. He struck the table with his open palm, sending a fork clattering onto the floor. Madison jumped, although her expression quickly settled into satisfaction. My mother pressed her lips together. I remained seated and asked whether we could continue the discussion without shouting. My father told me that he would not tolerate being lectured in his own home. When I gathered my statements, he followed me into the hallway, accusing me of thinking money made me superior to the rest of the family.
I went upstairs to collect my things, hoping distance would give everyone a chance to calm down. Instead, my father followed. He reached the guest bedroom before I had finished closing my suitcase, seized the handle, and carried it into the hall. I remember the small squeak of the wheels against the polished floor. Then he threw it down the staircase. My mother had followed us but made no attempt to stop him. Madison stood behind her, recording something on her phone until she noticed that I was looking.
By the time I reached the foyer, my father had announced that I was no longer welcome. He said a daughter who counted every dollar she spent on her parents did not deserve to belong to the family. For several seconds, I stared at him without answering. I could hear the refrigerator humming in the kitchen and a car passing outside. Those ordinary sounds seemed strangely distant. I wanted to ask whether he understood what he was saying, but his face told me that he did. He wanted his words to hurt.
I picked up the suitcase and extended its damaged handle. “All right,” I said. My father looked almost disappointed. He had expected an argument, perhaps an apology. Madison reminded me about the credit card. I reached into my purse, found my wallet, and checked that the card was still inside. Then I told her she would have to make other arrangements. She laughed, apparently convinced I was bluffing. My mother finally spoke, telling me not to be childish. I looked at the three of them and realized none had asked whether I had somewhere to go.
The evening air was colder than I expected. I carried my suitcase down the front steps, placed it in the trunk of my car, and sat behind the steering wheel without starting the engine. Through the large windows, I could see the dining room chandelier and the corner of the table where I had left my untouched dessert. My father’s house looked serene from the driveway. I had contributed toward its mortgage during difficult months, paid for repairs to the heating system, and covered the cost of replacing several windows. From outside, nothing suggested how much resentment had been waiting behind the front door.
I drove to my apartment across town. It was smaller than my parents’ home, with narrow kitchen counters and a balcony overlooking a row of older brick buildings. I had once considered buying something larger, but there always seemed to be another family emergency waiting for the money I managed to save. When I opened the door, I found the apartment exactly as I had left it: dishes drying beside the sink, a book facedown on the sofa, and a cardigan hanging over a chair. The quiet felt unfamiliar after the evening I had endured.
I made tea, although I could barely drink it, and opened my laptop at the kitchen table. My intention was to review the accounts before deciding what to do the next morning. Instead, I found myself staring at the login screen, thinking about how long I had been afraid of disappointing my parents. At twenty-seven, I had received my first substantial professional bonus. My father called the same evening to explain that his company needed emergency funding. I transferred most of the bonus before the money had even settled in my account.
Back then, he had thanked me. He had sounded embarrassed, almost tender, and promised that he would repay every dollar once the business recovered. I believed him because I wanted to. My father’s construction company had supported our family when Madison and I were growing up. Seeing him struggle frightened me. I knew employees depended on the business, and I understood that one failed contract could create problems far beyond his own finances. Helping seemed like the natural thing to do. I did not imagine that a temporary rescue would become the permanent arrangement governing our relationship.
The first year was difficult but understandable. The second brought improvements in the business, along with new requests. My parents renovated their kitchen. Madison needed help with tuition and living expenses. A family vacation became my responsibility because my father said everyone deserved time together after the stress of the previous year. Eventually, my mother stopped asking whether I could afford things. She simply informed me when a payment was due. I had accepted the change so gradually that I could not remember the precise moment generosity had turned into an expectation.
I opened a spreadsheet and began listing the arrangements. The mortgage assistance, car payments, insurance, credit card charges, transfers to Madison, and occasional payments to my father’s suppliers occupied separate rows. I worked carefully, checking each entry against bank records. It was the same method I used professionally when clients arrived with incomplete books and assurances that their problems were temporary. Seeing my family’s financial habits organized on a screen was different from remembering them one favor at a time. Individual emergencies had become a system.
Some entries surprised me. Others made me feel foolish for not examining them sooner. My mother’s card had been used at expensive restaurants and specialty stores. Madison had arranged recurring payments for services she had never mentioned. My father’s business had received financial support well after he told me its cash flow had improved. None of these charges alone explained the damage between us. Together, they showed how little anyone had considered the limits of my generosity. I closed my eyes and remembered my father saying I owed them everything.
At eleven that night, my mother sent a message. She said my father had been under tremendous pressure and that I should not take his words literally. She did not ask whether I was safe or apologize for what had happened. Instead, she reminded me that several family payments were scheduled for the following week and asked me not to create unnecessary complications. A second message arrived a minute later. Madison wanted to know whether she could use the card details stored on her phone since I had refused to leave the physical card behind.
I read both messages twice. My mother had apparently decided that being expelled from the family was an emotional matter, while continuing to pay its bills was a practical obligation. Madison seemed to think card access survived any disagreement. I had never clearly told either of them that the arrangement was ending. Perhaps I had encouraged their confidence through years of saying yes. But I had certainly not agreed to be financially responsible for them forever, and I could no longer pretend that silence would resolve the problem.
I called the number on the back of my credit card. A representative answered after a brief wait and asked how she could help. I explained that relatives had access to my card information, that I had withdrawn permission for them to make purchases, and that I needed the existing card canceled. She asked several questions, verified my identity, and described the difference between blocking a physical card and preventing additional charges through stored payment arrangements. We discussed recurring transactions, digital wallets, authorized users, and how to review purchases already posted.
For the first time that evening, I felt capable of making a decision without anticipating my father’s reaction. I requested a replacement card with a new number, asked for available merchant tokens and authorized-user access to be reviewed, and documented my concern about future unauthorized transactions. The representative explained which changes could be made immediately and which might require follow-up with individual merchants. I wrote everything down. Then I changed the passwords on accounts my family had used and began removing permissions that no longer made sense.
It was nearly two in the morning when I finished the first round of changes. My tea had gone cold, and the damaged suitcase stood beside the bedroom door, its broken wheel still missing. I should have been exhausted. Instead, I sat at my table with the spreadsheet open and considered the amount of money I had spent trying to keep my family happy. I could afford the losses, at least in the narrow sense that I was not facing bankruptcy. What frightened me was how readily I had allowed the arrangement to consume my time, my savings, and my ability to refuse.
Before going to bed, I opened the family group conversation one final time. Madison had sent a photograph of a handbag she wanted to buy the following afternoon. My mother had responded with a heart. My father had written that I would eventually come to my senses. I began typing an explanation, deleted it, and tried again. Finally, I sent a short message telling them that I would no longer pay their personal expenses and that they were not authorized to use my credit card or accounts. I asked that any genuine outstanding financial matters be put in writing.
My father’s reply arrived almost immediately. He accused me of deliberately trying to embarrass him and warned that family problems should remain private. Madison wrote that I was being selfish over something as insignificant as shopping. My mother sent only one sentence, telling me to reconsider before I did something I regretted. I did not answer. I saved the conversation, closed the laptop, and turned off the kitchen light. They still believed that enough pressure would make me reverse my decision, as it always had before.
The next morning, I woke to sunlight crossing my bedroom floor and a notification from my bank confirming changes to my account. For a moment, I reached for my phone expecting a message from my father asking me to come home. There was nothing of the kind. There were only payment reminders, a complaint from Madison about an interrupted subscription, and a note from my mother asking whether I had deliberately interfered with her shopping plans. I put the phone down. My family was beginning to notice the money had stopped, but none of them seemed to have noticed that I was gone.
END PART 1
PART 2 TITLE: When I Examined Seven Years of Family Expenses, I Discovered the Quiet Arrangements They Had Never Expected Me to Question
On Monday morning, my father’s construction company appeared on my caller ID before I had finished my first cup of coffee. The number belonged to the office, not his personal phone. I watched it ring until the call went to voicemail. Several minutes later, the office administrator left a message asking me to contact the company about an outstanding payment. Her voice was courteous and slightly embarrassed. She had been calling me about overdue invoices for years, and she probably assumed this was another ordinary request.
I listened to the message while standing beside my kitchen window. Below, delivery trucks were unloading groceries outside a small neighborhood market. Someone was arguing cheerfully with the driver about where to place a stack of crates. The world had resumed its usual Monday business, indifferent to the fact that my father had thrown me out of his life on Friday night. I wondered whether he had told his employees what happened. More likely, he had simply instructed the administrator to contact the person who always solved the company’s cash shortages.
I called her back and explained that I was no longer covering company expenses without a written agreement and a clear accounting of the amount owed. She hesitated, then said she understood. Before ending the call, she mentioned that the business had apparently expected another transfer from me before the end of the month. I asked who had told her that. After a pause, she admitted that my father had instructed her to include my contribution when preparing the payment schedule. I had never promised any such contribution.
That small exchange unsettled me more than I expected. My father did not merely hope I would help. He had incorporated my money into his business planning without asking whether it was available. I had spent years thinking of my assistance as voluntary. He had apparently begun treating it as predictable revenue. After we ended the call, I opened the financial records again and looked at the transfers I had made over the years. There were payments to suppliers, emergency deposits, equipment expenses, and direct transfers into the company account.
The earliest entries carried descriptions I remembered vividly. One had prevented a concrete supplier from suspending deliveries. Another had helped cover wages during a period when customers were late paying invoices. Those payments had frightened me at the time because I knew employees depended on the business. Later entries were less urgent. Some were listed simply as temporary assistance or cash flow support. I could not find repayment records for many of them. My father had occasionally promised to settle everything when the company was profitable, but he had never supplied a complete statement.
I arranged my records by year, then by recipient. I distinguished expenses paid on behalf of the business from those that belonged to my parents personally. It was painstaking work. Some older records required searching archived emails and downloading statements from accounts I rarely used anymore. I found messages in which my father thanked me for saving a contract, followed by others demanding immediate help as though payment were my duty. Reading them in sequence, I noticed a gradual change in tone that I had missed when the messages arrived months apart.
In the first year, he asked whether I could spare a particular amount. By the third, he wanted to know when the next transfer would arrive. By the fifth, he accused me of being unreliable whenever I requested supporting documents. The change had been slow enough to feel normal. Now I could see it clearly. My father’s gratitude had not disappeared overnight. It had been replaced, transaction by transaction, with the conviction that my earnings belonged partly to him.
My mother’s expenses were easier to trace because most had been charged through cards linked to accounts under my control. I knew about the SUV payments, although I had not appreciated the full cost once insurance, maintenance, and optional coverage were included. I also knew about her charitable events and lunches with friends. What surprised me were the number of smaller purchases at luxury stores. They arrived in clusters, usually around holidays, birthdays, or Madison’s visits. A few carried brief descriptions that made it impossible to identify the merchandise without requesting additional records.
Then there was the handbag. I opened the transaction details and looked at the date. The purchase had occurred on a Tuesday afternoon while I was in a client meeting. Later that evening, my mother had called to tell me about a household expense she needed help covering. She had sounded worried, describing unexpected costs and asking whether I could leave enough credit available for the following week. I remembered reassuring her that she could use the card for necessities. I had not known she had already spent twelve thousand dollars on an accessory.
I felt a familiar impulse to excuse her. My mother had grown up with very little money, and she had always associated beautiful things with security and success. When I was a child, she saved fashion magazines and admired expensive clothing she could not afford. After my father’s business became profitable, she developed a taste for the things she once considered unreachable. None of that made the unauthorized purchase acceptable, but understanding her habits was easier than acknowledging that she had deliberately concealed the truth from me.
Madison’s records were different. She rarely asked for money in large amounts. Instead, she created circumstances that required frequent, smaller interventions. An apartment deposit. A credit card payment. A vacation that had already been booked. A friend who supposedly needed repayment immediately. Whenever I hesitated, she reminded me that I was the older sister and that our parents expected us to support each other. She had a gift for making ordinary adult expenses sound like family emergencies. I usually discovered the unnecessary details only after the money had left my account.
I found several messages from Madison describing purchases as investments in her future. A professional wardrobe would help her meet influential people. A luxury apartment would improve her social opportunities. Travel was necessary for networking. She had explanations for everything, and my parents supported them because they believed she deserved a lifestyle matching the family’s reputation. My own spending attracted considerably more scrutiny. When I replaced an aging laptop, my father asked whether it was really necessary. When I considered moving to a larger apartment, my mother suggested I should save the money.
By Tuesday afternoon, I had assembled a preliminary summary. I stared at the totals, then checked several figures again because I wanted to be certain. The money I had given my family was substantial. More troubling than the amount was the pattern. My contributions had continued through periods when the family’s spending increased rather than decreased. The construction company had received support while my parents renovated their home. Madison had accepted transfers for basic expenses while taking expensive trips. Nobody had demonstrated a serious plan to become financially independent of me.
That evening, my mother called. I answered because I wanted to believe she might finally ask about what happened on Friday. Instead, she began by saying the card was no longer working properly. She had attempted to make a purchase and received a message requesting another payment method. I explained that I had canceled her access. There was a short silence. Then she asked why I would take such a drastic step when we had experienced nothing more than an unpleasant family argument.
I sat down at my kitchen table and reminded her that my father had told me to leave permanently. She sighed. “Your father says things when he’s upset, Emily. You know how he is.” I asked whether she had said anything to stop him. She replied that contradicting him would only have made the situation worse. I waited, hoping she might acknowledge that watching silently had hurt me. Instead, she asked whether I could arrange temporary access until she and Madison had finished several planned purchases.
I told her the account would remain closed to them. She became unusually quiet, then said I was allowing money to poison our relationship. I asked what relationship she thought we had when the first thing she wanted after my expulsion was access to my credit card. Her breathing changed. For a moment, I thought she might cry. Instead, she told me that I had become cold and suspicious since my career began improving. She said my father was disappointed in the woman I had become.
I wanted to argue. I wanted to describe every transfer, every missed holiday, every evening spent resolving problems that were not mine. But I had explained those things before, and repetition had never made them more willing to listen. I told my mother that I loved her, but that I would no longer finance purchases I had not agreed to. She asked whether that meant she would have to surrender the SUV. I said we would need to examine the loan documents and decide how to handle future payments properly. She ended the call without saying goodbye.
The following morning, Madison sent a series of increasingly irritated messages. She wanted access to her shopping accounts restored. She claimed that a merchant had refused to process an order because the payment card was inactive. I explained that she needed to provide her own payment information. She responded that she did not have enough available credit. When I suggested postponing the purchase, she accused me of deliberately humiliating her. She said she had already told several friends about the things she planned to buy.
I asked what the purchases were. She avoided the question. Instead, she insisted that I was wealthy enough to cover them without suffering any inconvenience. That was an argument I had heard throughout my adult life. My financial stability was treated as evidence that my money had no particular value to me. I had worked for it, saved it, paid taxes on it, and sacrificed personal opportunities to keep earning it. Yet my family’s conversations reduced those years of effort to a convenient figure they could spend whenever they wished.
I stopped responding and contacted the card issuer again. I wanted written confirmation that the replacement account could not be used by anyone who still possessed the old card details. The representative explained that merchants sometimes retain recurring-payment arrangements and that security measures should be reviewed individually. We discussed the steps required to prevent unauthorized purchases and document any attempts that occurred after permission had been withdrawn. I requested additional transaction alerts and arranged to review every active payment connection associated with the old card.
The process was more complicated than simply cutting up plastic. Digital wallets, shopping applications, recurring subscriptions, and saved merchant profiles had accumulated over years of casual use. Some were mine. Others belonged to relatives who had been given access for specific purposes. I checked each carefully, removing permissions where possible and contacting merchants when necessary. I also preserved screenshots of messages in which I had explicitly withdrawn authorization. The work was tedious, but I wanted a reliable record if anyone later claimed that a purchase had been approved.
That afternoon, I called the lender that financed my mother’s SUV. I requested the documents showing my obligations and the procedures for changing or ending the arrangement. The representative explained that I could not simply cancel a signed financing agreement because of a family dispute. Any change would require appropriate action under the contract. I appreciated the clarity. I had no intention of ignoring legitimate obligations. My concern was separating responsibilities I had formally accepted from informal expectations that my parents had transformed into permanent demands.
I made a list of accounts requiring additional attention. The SUV belonged on it, as did a few business arrangements involving money I had advanced. Other expenses were straightforward. My parents’ restaurants, Madison’s shopping, household entertainment subscriptions, and personal travel were not debts I had agreed to carry indefinitely. I could end those payments without pretending that every past contribution needed to be recovered. The distinction mattered. I was not looking for a way to hurt my family financially. I was trying to stop funding a lifestyle I could no longer reasonably support.
On Thursday, I received an email from my father. Unlike his angry messages over the weekend, this one was written in formal language. He reminded me of the sacrifices he and my mother had made throughout my childhood. He accused me of creating unnecessary tension and suggested that my recent behavior reflected poorly on my character. Then, near the end, he mentioned that the construction company was approaching an important payment deadline and that my assistance would be expected as usual.
I read the email several times, particularly the final paragraph. He had not apologized for expelling me. He had not acknowledged that I was no longer welcome in his house. Yet he still intended to use my money to satisfy a business obligation. I replied that any request for financial support would need a specific amount, documentation, and a written explanation of repayment terms. I added that I would not authorize further payments merely because the company had included them in its expectations. His response arrived within an hour.
He called my demand for documentation disrespectful. He wrote that a daughter should not approach her father’s problems as if he were a stranger seeking a commercial loan. Then he said something I would remember for a long time: if I wanted to behave like an outsider, perhaps I should accept that outsiders did not get to question family decisions. I stared at the contradiction. He wanted the unquestioning financial support of a daughter while denying me the right to participate in the family whose expenses I was expected to cover.
I did not reply immediately. Instead, I returned to the records. Several older transfers included brief notes promising repayment, but others were simply gifts I had willingly made. I knew it would be unfair to rewrite the history of every contribution because our relationship had deteriorated. What I could do was identify obligations that remained active and establish where my permission ended. I created a separate folder for contracts, another for messages, and a third for account statements. For once, I treated the family’s finances with the same care I gave my clients.
On Friday afternoon, I received a call from the card issuer’s security team. The representative explained that additional activity associated with the canceled card had been detected and that some merchant connections were still being reviewed. I confirmed that nobody in my family had permission to use my old account information. She asked whether I expected anyone to attempt another transaction. I said I did not know, although I suspected my mother and sister had not accepted the changes. She advised me to retain any relevant communications and monitor further alerts.
That evening, my mother sent a photograph of a luxury boutique’s reservation confirmation. Madison had arranged a private appointment for the following week, and my mother apparently assumed I would be impressed. Beneath the photograph, she wrote that the event was important to Madison and that an argument between adults should not interfere with a young woman’s opportunities. I looked at the confirmation and noticed that the appointment was scheduled for exactly two weeks after the night my father had thrown me out.
I asked whether Madison had arranged her own payment method. My mother replied that the boutique already had the family card on file, so there was no need to complicate matters. I reminded her that the card was canceled and that nobody was authorized to charge purchases to it. She dismissed the warning, saying the store had always processed their orders without difficulty. A moment later, Madison sent a photograph of several items she was considering. Their prices were visible. Together, they cost more than some people earned in several months.
I put the phone aside and walked onto my balcony. Traffic moved slowly through the intersection below, and the smell of bread drifted from a bakery closing for the evening. Somewhere in my parents’ house, my mother and sister were planning an expensive outing as if the financial arrangements between us had never changed. They had received my messages, encountered refused payments, and been told directly that permission was withdrawn. Still, they were preparing to use my account. Their confidence could no longer be explained by misunderstanding.
Before going inside, I opened the reservation photograph one final time and enlarged the lower corner. The boutique’s confirmation included a note identifying the payment method on file. It was the card I had canceled. My mother had sent the evidence herself, apparently without realizing its significance. I saved the image alongside her messages. Until that moment, I had thought the family’s attempts to use the account were careless remnants of an old arrangement. Now I knew they were proceeding with a planned luxury purchase despite being told, repeatedly, that the money was no longer available.
END PART 2
PART 3 TITLE: Two Weeks After I Was Disowned, a Boutique Called About the Card My Family Still Believed They Had the Right to Use
The first alert arrived at 11:18 on Friday morning, fourteen days after my father had ordered me out of his house. I was sitting in a conference room at work, reviewing a financial forecast with two colleagues, when my phone vibrated against the table. The notification identified an attempted transaction at a luxury boutique. The amount was $8,450. The request had been declined. I glanced at the screen, recognized the merchant from my mother’s reservation, and turned the phone facedown without interrupting the meeting.
Four minutes later, another notification appeared. This time, the requested amount was $6,980. It came from the same store and had also been refused. I excused myself, walked into the corridor, and opened the banking application. Both attempts were associated with credentials from the canceled account. Neither had produced a completed charge. I checked the timestamps, saved the alerts, and contacted the security department using the number displayed in my banking application. I did not want assumptions or anger to interfere with the facts.
The representative verified my identity and reviewed the activity with me. She explained that the attempts appeared to come from the merchant’s payment system, where my old card information had been stored. The account protections had worked, but the activity required confirmation because someone was still trying to use the invalid credentials. I explained that I had explicitly withdrawn authorization from the family members who previously had access. She documented my statement and confirmed that further attempts would remain subject to the bank’s security controls.
While I was speaking, my mother called twice. I ignored the calls until my conversation with the representative was finished. A third call came from Madison. Then a message appeared from my father, demanding that I answer my mother’s phone immediately. I stood near the office windows and watched clouds move across the neighboring buildings. I could imagine the scene inside the boutique: my mother dressed carefully for the appointment, Madison admiring expensive merchandise, and a sales associate explaining that the expected payment was unavailable.
When I finally called my mother, she answered before the first ring had finished. “Emily, something is wrong with the card,” she said. Her voice was low and urgent. In the background, I heard music and the soft murmur of other shoppers. I asked whether she had attempted to pay for merchandise using my old account. She hesitated, then said the boutique was holding several items and that the transaction needed to be completed immediately. I told her the account was canceled, exactly as I had explained in my earlier messages.
She sounded genuinely astonished. “You actually went through with it?” I reminded her that I had notified her when I canceled the card and again when she sent me the boutique reservation. She said she believed I was only trying to make a point. According to her, our family had disagreements all the time, but practical matters always continued as usual. She had not expected me to interfere with an appointment that she and Madison had planned so carefully.
I asked whether either of them had brought another way to pay. My mother became offended. She said she was not carrying enough money for the items Madison wanted and that the boutique had already set them aside. When I suggested they simply leave without buying anything, she told me I did not understand how humiliating that would be. I listened to her describe the inconvenience of an unsuccessful luxury purchase and remembered the night she had watched my suitcase tumble down the stairs without offering a word of objection.
Madison took the telephone from her. “Can you stop trying to punish everyone for five minutes?” she demanded. I asked whether she understood that the money was mine and that I had never authorized the purchases she was attempting. She replied that I had always paid for family expenses before. I told her previous generosity was not permanent permission. Her response was immediate. She accused me of treating her like a criminal and said everyone at the boutique was staring at them because I had decided to create a scene.
I could hear my mother telling her to lower her voice. Then Madison said something that clarified the situation completely. She admitted that she had known the card was canceled but thought the boutique could still process the saved payment details. She had assumed the transaction would go through because the store had successfully charged the account in the past. I asked why she had proceeded after being told she no longer had permission. She replied that she had not believed I would actually refuse to pay.
For several seconds, neither of us spoke. The admission was so plain that I did not need to argue about intent. Madison had not forgotten the new arrangement. She had deliberately tested whether the old one still worked. I asked her to put our mother back on the telephone. When she did, I explained that no further charges would be accepted and that I had already documented the attempted transactions with the card issuer. My mother said I was overreacting and asked whether I could make an exception for that afternoon.
I told her no. She asked again, this time more softly, whether I could at least pay for one item so Madison would not leave empty-handed. I said the answer was still no. Then I asked my mother whether she had anything to say about the way my father had treated me two weeks earlier. The question seemed to confuse her. She reminded me that he had been angry and insisted we could discuss everything once the shopping problem was resolved. I realized that she considered reconciliation something she could postpone until it became useful.
I ended the call and returned to my meeting. The financial forecast on the conference room screen seemed suddenly straightforward. There were identifiable costs, clear assumptions, and decisions that could be supported by evidence. I had spent years helping clients separate wishes from resources, yet I had allowed my own family to disregard that distinction entirely. When one of my colleagues asked whether everything was all right, I said there was a personal matter requiring attention but that it was under control. For the first time, I believed that answer.
At lunchtime, my phone contained nineteen missed calls. Madison had sent a photograph of an expensive handbag she claimed had been reserved especially for her. My mother had written several messages describing the embarrassment of being refused payment in front of sales staff. My father had left a voicemail in which he accused me of publicly humiliating both women. He said my behavior was malicious and suggested that an adult daughter who deliberately shamed her parents did not deserve their affection or respect.
I listened to the voicemail in my office with the door closed. What struck me was the absence of any concern about the attempted purchases themselves. My father did not ask why the women had tried to use a canceled card. He did not acknowledge that I had explicitly withdrawn permission. To him, the injury was that the payment had failed where other people could witness it. He spoke about the family’s reputation as if that reputation entitled them to spend my money without asking.
I began drafting a response, then stopped. I knew what would happen if I called him while he was angry. He would demand obedience, I would attempt to explain the facts, and he would reinterpret every answer as evidence of disrespect. We had followed that pattern for years. Instead, I wrote a short email confirming that the card had been canceled and that no member of the family was permitted to use my account information. I included the date of my original notice and asked them to remove the credentials from every shopping account and device.
I sent the message to all three of them. Within minutes, Madison replied that I was behaving like a lawyer rather than a sister. My mother accused me of making ordinary family arrangements unnecessarily formal. My father wrote that he would not be intimidated by emails from his own child. Then he reminded me, once again, that he had provided for me when I was young. I did not answer. Their responses were useful because they showed that everyone had received my instructions, even if nobody was willing to respect them.
By late afternoon, I had obtained a summary of the attempted transactions from the issuer and requested that the information be preserved. I also contacted the boutique to make certain the old card details were removed from any customer profile associated with my name. The store manager was courteous. She confirmed that my payment information had been retained from previous purchases and said the business would follow its procedures for removing it. I thanked her and asked that no future transaction be processed on my behalf without my direct authorization.
The manager hesitated before ending the call. She said there had been confusion during the appointment because the customers had presented themselves as members of the cardholder’s immediate family and had insisted that payment permission remained valid. I told her that the permission had been withdrawn. She said the store would document that information. I could hear no judgment in her voice, only the caution of someone who understood that an expensive transaction could become a serious dispute when the person expected to pay had not agreed.
After work, I stopped at a grocery store near my apartment. I needed bread, milk, and something for dinner. Standing in the checkout line with a small basket, I noticed how ordinary it felt to pay for my own purchases. The cashier asked whether I wanted a receipt. I said yes, folded it into my wallet, and walked home through the early evening traffic. For years, I had been so accustomed to receiving demands for money that ordinary transactions had acquired a strange emotional weight. Now I found myself grateful for the simplicity of choosing what I bought.
At home, I placed my groceries on the counter and opened the messages my family had sent throughout the afternoon. Madison had moved from anger to wounded disappointment. She said she could not believe I would embarrass her over money when I knew how important appearances were to her. My mother had sent a longer message explaining that she had dedicated her life to providing a beautiful home for our family. She described the private shopping appointment as a rare opportunity, although the purchase records showed that luxury shopping had become a regular activity.
My father’s final message was shorter. He wrote that I had two days to correct the situation and apologize. He did not specify what correction he expected, but I understood. He wanted the financial arrangements restored, the boutique incident forgotten, and my behavior treated as the real offense. I read the message while standing beside my kitchen sink. Outside, the city was growing dark. I thought about how often he had used deadlines and anger to force quick decisions, particularly when money was involved. This time, I had no reason to hurry.
Instead of replying, I opened the records from my father’s construction company. The earlier payments were organized now, and I had begun reconciling them with the documents I still possessed. Several substantial contributions had been made during periods when he claimed to be struggling. I remembered visiting the office on one occasion and seeing employees anxious about their paychecks. At the time, I had transferred funds because I genuinely feared people would lose their jobs. Those were decisions I could still defend, regardless of my father’s later behavior.
Other transfers were harder to explain. They had been requested without supporting invoices, often immediately before family celebrations or large personal expenses. I could not assume that one transaction had financed another simply because the dates were close. Nevertheless, the timing raised questions that deserved answers. I wanted to know how much support had gone toward the company’s legitimate needs and how much had allowed my parents to continue spending freely while describing themselves as financially strained.
I wrote to my father requesting an updated summary of the money I had advanced to the company, including any repayments and the status of outstanding obligations. I kept the language professional. I did not accuse him of misconduct or demand immediate repayment of every dollar. I simply wanted the records. His answer arrived surprisingly quickly. He said the company had no obligation to provide internal financial information to someone who no longer wanted to behave like a member of the family.
I stared at that sentence. It was extraordinary how easily my status changed depending on what he needed. When he wanted money, I was his daughter and therefore obligated to help. When I requested information, I was an outsider who had no right to ask questions. I replied that I was seeking records relating to my own payments, not unrestricted access to his business. I attached several transfer confirmations. He did not answer directly. Instead, he sent another message saying I was attempting to undermine him during a difficult period.
The next morning, I received a call from a supplier who had done business with my father’s company for years. He had my number because I had personally helped settle an overdue invoice during an earlier crisis. He sounded uncomfortable and explained that the company was behind on another payment. My father had apparently told him that I would help resolve the matter, as I had done before. The supplier wanted to know whether he should expect funds from me before the end of the following week.
I told him I had not agreed to provide any money and asked that future payment arrangements be discussed directly with the company. He apologized, saying he had understood that I remained involved in supporting the business. Before hanging up, he mentioned that my father had become unusually concerned about several upcoming obligations. I thanked him for the information but avoided discussing family matters. The call left me troubled. The construction company was apparently still relying on promises my father had made in my name.
That afternoon, my mother contacted me again. She had heard that I was refusing to help the business and wanted to know why I was making everything worse. I reminded her that my father had disowned me, that I had asked for basic financial records, and that he had refused to provide them. She said I should understand how proud he was and how difficult it was for him to ask for help. I told her that pride did not excuse expecting someone else’s money without consent. She responded that I sounded determined to destroy everything we had built together.
I asked her what she meant by together. The house belonged to my parents. The construction company belonged to my father. Madison controlled her own personal decisions. I had no meaningful voice in their spending, yet my savings were repeatedly used to resolve the consequences. My mother said I was focusing on legal ownership rather than emotional bonds. I asked whether those emotional bonds had mattered when my father ordered me out. She became quiet again, then said he would eventually calm down if I stopped provoking him.
On Sunday evening, my father finally called me directly. I answered because I wanted to hear whether anything had changed. He sounded tired, but his voice was still firm. He began by saying that my mother had been humiliated and that Madison was deeply upset. Then he moved quickly to the company’s financial problems. He said several payments were approaching and that my refusal to help was putting the business at risk. I asked him to send the relevant documents so I could understand the situation before discussing any possible arrangement.
His answer came in a sharp burst of anger. He said he would not beg his own daughter for money or submit to an interrogation about his business. I reminded him that I had not demanded anything unreasonable. I was simply unwilling to provide financial support without understanding the obligation. He told me that if I continued behaving this way, I would be responsible for whatever happened next. I looked at the spreadsheet open on my table and said I could not be responsible for business commitments I had neither approved nor made.
For the first time during the conversation, he hesitated. Then he told me something I had not known. He had already informed several people that I would help cover the company’s upcoming expenses. He claimed he had made those assurances because my support had always been reliable. I asked whether he understood the difference between past assistance and a future promise made without my knowledge. He told me not to lecture him. I asked how much money he had committed on my behalf. He refused to give me a figure.
After we ended the call, I sat motionless for several minutes. The failed boutique purchases had shown me that my family considered access to my money a continuing privilege. My father’s admission suggested the problem extended beyond shopping. He had been assuring business contacts that I would provide funds without confirming my agreement. I opened a fresh document and wrote down his exact words while I could still remember them. Then I gathered the company records, the banking alerts, and the messages from my family. I needed independent advice before the situation became more complicated.
END PART 3
PART 4 TITLE: I Thought Canceling My Card Would End the Argument, Until My Father’s Financial Promises Revealed a More Serious Problem
On Monday morning, I carried a folder of financial records into a small law office on the fourth floor of an older downtown building. The receptionist offered me coffee and directed me toward a conference room overlooking the street. I had slept badly the previous night, turning my father’s words over in my mind. He had promised other people that I would cover his company’s obligations. I wanted to know what those promises meant for me, particularly if someone believed I had personally agreed to make payments.
The attorney I met, Mara Ellis, specialized in financial disputes and commercial agreements. She was a woman in her early forties with a practical manner and a habit of reading documents before offering opinions. I appreciated that immediately. She listened while I explained the history of my father’s company, the years of financial assistance, the credit card arrangements, and the argument that had ended with my expulsion. When I finished, she asked a simple question. “What outcome are you hoping for, Emily?”
I had prepared explanations for everything except that. I looked down at my hands, resting beside the folder. I did not want my parents to lose their home. I did not want my father’s employees to suffer because his company struggled. I did not want Madison to face financial disaster merely because she had become accustomed to living beyond her means. But I also knew that protecting them from every consequence would mean continuing the arrangement that had brought us here. I told Mara I wanted my family’s obligations separated from my own, with no further use of my money without permission.
She nodded and began examining the records. We reviewed the documents connected to my mother’s SUV first. Mara explained that the obligations I had accepted under the financing agreement needed to be handled according to its terms. Stopping an informal payment arrangement and ending a legally binding contract were different matters. We discussed options for resolving that obligation properly, including the possibility of refinancing or another arrangement acceptable to the lender. It was not the immediate escape I might have wished for, but it was an answer based on facts.
Next came the construction company. Mara examined copies of bank transfers, old messages, and the limited agreements I possessed. She explained that my previous financial contributions did not automatically authorize my father to promise future funding. At the same time, she wanted to review any signed guarantees, loans, or other documents before drawing conclusions about particular obligations. I told her I had never knowingly agreed to serve as a continuing source of money for the business. She said that made obtaining the complete records especially important.
We spent considerable time on the credit card. Mara asked whether I had previously allowed my mother and sister to make purchases. I admitted that I had, although the permission was never intended to include unlimited luxury spending. She explained that past charges could require individual examination because authorization was not always as simple as whether the cardholder personally selected the merchandise. I could not automatically treat every regretted purchase as fraud. However, the messages withdrawing future permission and the later attempts to use the canceled card were significant facts worth preserving.
I showed her the boutique reservation and the alerts from the day my mother and Madison attempted the purchases. She read the messages slowly, paying particular attention to Madison’s admission that she had known the card was canceled. Then she examined the email I had sent explicitly prohibiting further use. She advised me to continue following the issuer’s dispute procedures and avoid making accusations I could not substantiate. Her calmness helped. I had been worried that setting boundaries meant preparing for a confrontation. Instead, much of the necessary work involved documenting what I knew and refusing to make promises under pressure.
Before I left, Mara suggested communicating with my family in writing wherever possible. She also recommended providing clear notice to any business contacts who might mistakenly believe I had authorized payments on my father’s behalf. I asked whether doing that would humiliate him. She looked at me over the documents. “Correcting a false assumption about your own financial obligations isn’t an attack,” she said. I knew she was right, but the question had revealed something uncomfortable about me. Even after everything that happened, I was still arranging my decisions around my father’s pride.
I returned to work and spent the afternoon dealing with ordinary client responsibilities. At five, I opened my personal email and found several messages from the construction company’s office. The administrator had forwarded payment requests and supplier correspondence that mentioned my assistance. I had asked for relevant records, and she had apparently interpreted that request more seriously than my father had. Her email was polite, with a brief note explaining that she wanted to avoid further confusion about who was responsible for the outstanding balances.
The documents showed that the business was under pressure. Payments from customers had been delayed, suppliers were becoming impatient, and several operating expenses were approaching. I could understand why my father was concerned. The company had faced similar problems before, and I knew how quickly a shortage of working capital could affect employees. Nevertheless, something about the payment schedule troubled me. Several projected expenses were matched against expected outside support rather than confirmed business income. I wanted to know exactly what those entries represented before drawing conclusions.
I called the administrator the following morning. She sounded relieved to hear from me and apologized for involving me in family matters. I told her she had done nothing wrong. Then I asked who prepared the forecasts. She explained that my father reviewed them with the company’s accounting staff. When I asked about the expected outside support, she said it referred to contributions he anticipated receiving from me. I asked whether she had ever seen a signed commitment. She said she had not handled the underlying documents and assumed my father had made the arrangements personally.
I thanked her and asked that my name not be treated as a confirmed source of future funding without my written approval. She agreed to pass the message along. After ending the call, I sat with the schedule open in front of me. My father had never discussed those projected contributions with me. He had simply built them into the company’s plans. I could sympathize with the business’s difficulties, but I could no longer ignore the risk created when people treated an unconfirmed family contribution as money already available.
That afternoon, I sent my father a formal request for the records supporting any commitments he believed I had made. I kept the message short and factual. I also offered to discuss legitimate obligations through a scheduled meeting, provided we could focus on documents rather than accusations about loyalty. He did not respond until late that evening. When his answer arrived, it contained no financial records. He said I had embarrassed my mother, hurt my sister, and now appeared determined to interfere with his professional relationships.
He added that if I wanted a family again, I needed to begin by apologizing. I read that line several times. It was the first time he had explicitly suggested that my place in the family depended on restoring the arrangement he preferred. I had known he believed that, but seeing the condition in writing made it harder to dismiss as something said in anger. I responded that I was willing to discuss our relationship separately from financial obligations. I would not agree to pay personal expenses or business debts simply to regain his approval.
My mother called the next morning. This time, her voice lacked the sharp certainty I had heard during the boutique incident. She said the house felt uncomfortable without me and that my father had been sleeping badly. Madison was upset, too, although my mother did not explain why. For a few minutes, we spoke almost normally. She asked whether I had been eating properly and whether work was going well. I told her about a difficult project and listened while she described a neighbor’s recent visit. The ordinary conversation made me unexpectedly sad.
Then she asked whether I could arrange a temporary payment card while we worked through our differences. She said the household had several upcoming expenses and that dealing with them personally was becoming stressful. I looked toward the folder on my desk. My mother had managed to ask about my life for several minutes before returning to the subject she seemed unable to leave alone. I told her that I would not reopen the card or provide another one. She sighed and asked why I insisted on making life harder for everyone.
I reminded her that she and Madison had attempted luxury purchases after being told the account was closed. She replied that they had been embarrassed and that Madison had cried afterward. I asked whether Madison was upset about losing her sister or losing access to expensive things. My mother said I was being unfair. I did not press the question. Instead, I asked her to think about why both women had continued shopping when they knew I had withdrawn permission. She was quiet for so long that I thought the call had disconnected.
Finally, she admitted that they had assumed I would change my mind. It was the closest she had come to acknowledging the truth. She said I had always been dependable and that my father believed I would eventually put the family first. I asked whether putting the family first meant allowing them to spend money without consulting me. She did not answer directly. She said our family had never been perfect and that every relationship required sacrifices. I told her I agreed, but that sacrifices should not always be demanded from the same person.
Before ending the call, I mentioned the twelve-thousand-dollar handbag. My mother sounded startled. She asked why I was returning to something that had already happened. I told her the purchase mattered because she had described it as a household necessity when requesting access to my money. She replied that she had wanted something special and had not expected me to object. I said the issue was not whether she deserved beautiful things. It was whether she had the right to decide that I would pay for them without knowing what I was buying.
Her voice became unsteady. She said she was beginning to feel as though everything she had ever done as a mother was being measured against a credit card statement. I told her that was not what I wanted. I remembered her helping me with school assignments, sitting beside my bed when I was ill, and staying awake until I arrived home safely as a teenager. Those memories mattered to me. So did the fact that she had stood silently while my father threw me out. Loving someone did not require pretending the hurtful parts of our relationship had never happened.
For a moment, I thought she might apologize. Instead, she said my father would be willing to meet if I approached him respectfully. I agreed to a discussion but suggested a neutral location. She seemed relieved and promised to arrange it. The following day, we settled on a quiet meeting room in a business center near downtown. I told her I would bring copies of the relevant financial records and that I expected everyone to remain civil. She said she understood. I was less certain that my father would.
He arrived ten minutes late, carrying no documents. My mother walked beside him with the cream-colored handbag on her arm. Madison followed, looking irritated, and took a seat near the door. I had arrived early and arranged my folders on the table. When my father entered, he looked around the room and asked why I had insisted on meeting somewhere so impersonal. I explained that I wanted a place where we could discuss difficult matters without anyone being ordered to leave.
He did not appreciate the reference. He sat down heavily and said we should finish quickly because he had work to do. My mother placed her handbag on the table. Madison opened her phone. I began by explaining that I was not asking them to repay every gift I had ever made. I wanted to establish which obligations were legally mine, which expenses belonged to them, and how we could prevent further unauthorized use of my accounts. My father interrupted before I had finished, saying the family had never needed contracts to take care of one another.
I opened the folder containing the credit card alerts and placed copies in front of him. I explained what happened at the boutique and why the bank had declined the transactions. Madison immediately accused me of trying to make her look dishonest. I reminded her that she had admitted knowing the card was canceled. She said she had believed I would eventually approve the purchases. My father told me to stop interrogating her. He said the money would have made little difference to me and that refusing to help had been needlessly cruel.
I asked him whether he had any idea how much I had paid toward the family’s expenses over the previous seven years. He said he did not need a financial summary to know that I had helped. I showed him the records anyway. He examined the first page, then pushed it aside. My mother leaned forward and studied the figures more carefully. Madison barely looked. My father said the numbers proved only that I had been fortunate enough to earn a good living and share some of it with the people who raised me.
I explained that I had given the money willingly at first, particularly when the construction company was in genuine difficulty. What had changed was the assumption that I would always pay, regardless of the reason or my own priorities. My father said he had never forced me to provide anything. I reminded him that he had just threatened to exclude me from the family unless I apologized and restored the arrangements. He answered that I was twisting his words. My mother reached toward his arm, but he moved away.
The discussion turned to the business. I asked how much financial support he had promised suppliers and employees on my behalf. He said it was normal for a business owner to plan around dependable resources. I replied that I was not a company resource. I was a separate person who needed to approve any financial commitment before he represented it as available. His expression changed. He told me that I was behaving as though he were trying to cheat me. I said I wanted to see the documents supporting his claims.
For the first time, he admitted that he had assumed I would provide additional money because I had never refused him before. He said he had made arrangements based on that expectation and that withdrawing my support had placed him in an impossible position. I felt sympathy for the predicament, but I also knew I had not created it alone. He had chosen to make promises without consulting me. I told him I would review genuine contractual obligations, but I could not accept responsibility for expectations he had created privately.
Madison interrupted, asking whether all of this meant she would no longer receive help with her expenses. I looked at her and said I would not continue paying for her discretionary purchases. If she needed support for a genuine emergency, she could discuss it honestly with me, but nothing would be automatic. She laughed without amusement and said I was treating her like a stranger. I told her that strangers usually asked permission before charging thousands of dollars to someone else’s account. She stared at me, then looked away.
My mother began to cry quietly. She said she had never expected money to divide her daughters or destroy her marriage’s peace. I wanted to comfort her, but I could not pretend the problem had appeared because I finally refused to pay. I told her that the family could survive without luxury purchases and that my father’s business deserved a sustainable plan rather than repeated emergency transfers from me. She dabbed at her eyes and said she did not know how things had become so difficult. I wished she had asked that question years earlier.
My father stood abruptly. He said he was finished listening to accusations in a rented conference room. He told me that if I wanted to live independently, I should stop expecting the family to welcome me back whenever I found it convenient. I reminded him that I had not asked to be expelled. He looked at me for a long moment, then said I had brought the situation upon myself by refusing to respect him. He left without taking any of the documents. Madison followed almost immediately.
My mother remained in her chair. The meeting room was quiet except for the low hum of the ventilation system. She touched the handle of her handbag, then moved her hand away. She asked whether I would still speak to her after everything that happened. I told her I was not trying to punish her with silence, but that future contact could not depend on my willingness to pay. She nodded slowly. Before leaving, she said she had not understood how serious I was until the boutique refused the card. I believed her. That was part of what hurt.
I stayed behind to gather the records. The meeting had not produced an apology or a financial agreement, but several things were clearer. My father had acknowledged making plans around money I had not promised. Madison had confirmed that she expected continued support. My mother had finally admitted that she considered my warnings temporary. None of them could reasonably claim they had misunderstood my position. I placed the documents back in their folders, took a photograph of the empty table for my own records, and returned to the office.
Later that afternoon, the construction company’s administrator sent another email. She had found additional material relating to the projected outside support I had questioned. The message included a spreadsheet and several pages of correspondence. I opened the attachments, expecting another list of unpaid invoices. Instead, I found a payment schedule showing a substantial amount assigned to me as an anticipated source of funding. Beside the amount was a note stating that the company’s owner had confirmed my participation.
I examined the dates. The schedule had been prepared before my father threw me out, but some of its assumptions had been circulated to suppliers afterward. I could understand how the company might have relied on past contributions when creating an internal forecast. What troubled me was that the documents presented my participation as settled, even though I had never been asked to approve it. I searched the attachments for a written agreement, a signed promise, or anything showing that the commitment had actually come from me.
Near the end of the correspondence, I found a forwarded message in which my father assured a supplier that the family funding was secure. He had written that I remained committed to helping the company and that payment would arrive according to the schedule. The message was dated several days after he had ordered me out of his house. By then, I had already sent written notice explaining that I would not authorize additional support without reviewing the documents. He had apparently chosen to ignore that notice and continue making assurances in my name.
I called Mara and described what I had found. She asked me to forward the correspondence and preserve the original attachments. She explained that the precise wording and any representations made to outside parties would need careful examination. We should not assume that an inaccurate business forecast was the same as a legally enforceable promise, but neither should we ignore the possibility that someone had relied on statements about my participation. I agreed and sent her the documents while we were still speaking.
After ending the call, I returned to the attachments and noticed a separate document I had overlooked. It was labeled as a funding authorization and carried my full name, Emily Bennett, beneath a statement approving the company’s anticipated financial support. The page looked formal, with spaces for dates and signatures. I enlarged it on my screen. A signature appeared where mine was supposed to be. I examined the handwriting, the angle of the letters, and the unusual final stroke. It resembled my signature closely enough to make my stomach tighten.
I had never seen that document before.
I checked the date again, then searched my emails, records, and electronic signing accounts for any corresponding authorization. Nothing appeared. I remembered signing documents years earlier when I helped the company through its original crisis, but this authorization concerned a different period and a new commitment. I had not approved it. I had not attended a meeting about it. Yet the document appeared to have been prepared and circulated as evidence that my support was guaranteed.
For several minutes, I sat staring at the signature. I did not know who had placed it there or whether the document had been presented as a binding agreement. I understood enough about financial records to know that conclusions required evidence, not suspicion. But I also knew that the signature was not one I had knowingly provided. I saved the attachment, copied the correspondence into a separate evidence folder, and sent Mara a follow-up message identifying the page that concerned me most.
My phone rang before I could close the file. It was my father. I let the call go to voicemail. When I listened, his tone had changed from anger to something more controlled. He said we needed to talk privately about the construction company and that bringing lawyers into family business would only make matters worse. He told me there were things I did not understand and asked me not to contact anyone else until we had spoken. I listened twice, then saved the recording beside the documents he had refused to discuss at our meeting.
I looked at the disputed authorization on my screen and thought about the last two weeks. My family had continued trying to spend money after I withdrew permission. My father had made financial assurances without consulting me. Now there was a document bearing a signature I had not knowingly given. Whatever explanation existed, the matter could no longer be resolved through another conversation in which I was expected to trust everyone and ask no questions. I replied that any discussion would need to include the relevant records and that I would obtain independent advice.
Then I sent Mara the remaining attachments and asked her to review the authorization before I responded further. I also requested that the company’s office preserve the original records. I did not accuse my father of forging anything. I did not threaten him or agree to another transfer. I simply stopped allowing the family relationship to replace the documentation that every serious financial commitment required. For the first time, I was willing to let the facts determine what happened next, even if the answers changed the way I understood the people who had raised me.
END PART 4
PART 5 TITLE: The Signature on My Father’s Funding Agreement Looked Familiar, but One Small Detail Revealed Why He Feared an Independent Review
Mara called shortly after eight the following morning. I had been awake since five, moving between my kitchen table and the window without accomplishing much of anything. The documents from my father’s construction company lay in three neat stacks beside my laptop. I had examined the disputed authorization so many times that the signature was beginning to look ordinary. When Mara asked whether I could come to her office, I put the papers into my bag and left without finishing breakfast. Something in her voice suggested that the document deserved more attention than we had initially expected.
Her office was quiet when I arrived. Rain moved across the windows in thin, uneven lines, and the receptionist was carrying a box of files into a storage room. Mara met me at the conference table with a fresh printout of the authorization and two older documents I had previously provided. She did not immediately offer an opinion. Instead, she placed the papers side by side and asked me to examine the signatures without looking at the surrounding text. I leaned forward, aware that she was watching my reaction rather than directing it.
The first document was from an equipment financing arrangement I had helped my father resolve nearly six years earlier. I remembered signing it at the construction company’s office, using a black pen that skipped slightly across the paper. The second was a release confirming that a particular obligation had been settled. The third was the new funding authorization. At first, all three signatures appeared plausible. Then I noticed something that made me stop. The disputed signature contained the same tiny break in the final stroke as the signature on the older release.
I looked closer. The letters did not merely resemble one another. Their spacing, angle, and proportions appeared almost identical, including an unusual hesitation where I had lifted the pen. Even the slight irregularity in the final letter was repeated. I had signed hundreds of documents over the years, and no two signatures were exactly alike. Mara pointed out that a visual comparison alone could not establish how the new signature had been produced. A qualified document examiner would need to assess the source materials. Nevertheless, the similarity justified further investigation.
I remembered the afternoon I signed the original release. My father’s office smelled of fresh paint because the reception area had recently been renovated. He had been unusually cheerful, pleased that a difficult financing problem was finally behind him. His administrator had scanned the signed papers before handing me a copy. At the time, I considered the procedure routine. Now, sitting in Mara’s office, I wondered whether that scanned document had remained available in the company’s files. I could not prove anyone had copied my signature, but I knew precisely where a usable image might have originated.
Mara asked whether I recognized the lender named in the new paperwork. I did not. The company was a commercial financing institution that specialized in business refinancing and secured lending. Its name appeared several times in the correspondence, along with references to a proposed consolidation of existing obligations. My father had told me the company was facing upcoming payments, but he had never mentioned seeking a substantial refinancing arrangement. I had assumed he wanted another temporary transfer to cover suppliers and wages. The documents suggested he was pursuing something more extensive.
We reviewed the pages describing the proposed transaction. The funding authorization was presented as evidence that I supported the company’s financial arrangements and would provide additional resources if required. Elsewhere, the refinancing materials referred to outside financial backing and a possible personal guarantee. Mara was careful to distinguish preliminary statements from enforceable commitments. She did not tell me I was legally responsible for anything merely because my name appeared in the packet. What concerned her was that a lender might be evaluating the company’s financial position based on an authorization I had never knowingly given.
I asked whether my father could have created a binding obligation using a copied signature. Mara explained that the answer depended on the actual documents, how they were delivered, the lender’s verification procedures, and other facts we had not yet established. A forged or otherwise unauthorized signature could create serious problems, but it would not automatically make every proposed obligation valid against me. The important thing was to notify the lender promptly, preserve evidence, and avoid any communication that could be interpreted as ratifying an agreement. She proposed preparing a written notice that afternoon.
Before leaving, I asked why my father would involve me in a refinancing transaction without permission. Mara closed the folder. She said there were several possible explanations, some less serious than others. Perhaps someone had reused an old form carelessly. Perhaps the company had incorrectly assumed my continuing support. Or perhaps a person had deliberately represented my agreement to strengthen the application. She would not choose among those possibilities without evidence. I appreciated her restraint, although I was beginning to fear what a proper examination might uncover.
Back at work, I found a message from my father’s office administrator. She wanted to know whether I had received all the attachments because two additional pages had been located in an archived folder. Her note was brief, but she mentioned that the company had been gathering refinancing records for several months. I asked her to preserve the original electronic files and any correspondence showing when they were created or transmitted. She replied that she would follow company procedures. I forwarded the exchange to Mara rather than attempting to investigate through the administrator myself.
That evening, I met with Rachel Morgan, a forensic accountant Mara had recommended. Rachel was in her late thirties, with a measured way of speaking and the remarkable ability to notice inconsistencies without announcing them as discoveries. We sat in a quiet restaurant near my office. She ordered tea, opened a notebook, and asked me to explain the situation from the beginning. Unlike my family, she did not interrupt when I described the years of financial support. She also did not express surprise when I explained that I had continued helping after the company appeared to recover.
Rachel asked questions that were uncomfortable precisely because they were practical. Had I treated the early transfers as loans? Had I received promissory notes? Were there repayment schedules? Had I ever been shown complete company accounts? Did I hold any ownership interest? I explained that I had been told the money would be repaid but had never received a consistent accounting. I had signed certain financing documents during the original crisis, but I did not knowingly own shares in the company or control its operations. Rachel wrote that down and asked to examine the original agreements.
She looked particularly interested in the gap between the company’s reported need for assistance and the family’s personal spending. I showed her the SUV payments, my mother’s luxury purchases, and the transfers to Madison. Rachel separated those records from the company documents immediately. She explained that wasteful personal spending was not, by itself, proof that business funds had been misused. We needed to establish which accounts paid which expenses and whether the accounting treatment matched the underlying transactions. I told her I did not want an exaggerated accusation. I wanted the truth.
Over the following two days, Rachel reconstructed a timeline using the records I possessed. We identified periods when my father requested urgent assistance, compared those requests with supplier correspondence, and noted the dates of transfers into the company. Some payments aligned with genuine operating difficulties. Others lacked clear supporting documentation. Rachel marked those entries for further review instead of labeling them improper. Her method was almost painfully patient. She wanted the evidence to explain itself before anyone decided what it meant.
Meanwhile, my family’s messages became more frequent. My mother asked whether I could meet her for lunch without discussing lawyers or financial records. Madison sent a long complaint about the card cancellation, followed by a photograph of a cheaper handbag she suggested I might purchase as a peace offering. My father left two voicemails insisting that I stop interfering with the company’s refinancing arrangements. In the second, he said the lender was beginning to ask unnecessary questions. He wanted me to call immediately and confirm that my support had not changed.
I listened to the message while Rachel reviewed a bank statement at my table. When it ended, she looked up and asked whether I had ever promised to support the refinancing. I said no. She asked whether I had signed anything relating to the new application. Again, no. She advised me to preserve the voicemail and let Mara handle communications about the transaction. I was relieved that someone was willing to treat my father’s demands as statements requiring verification rather than instructions I was expected to obey.
The lender received our formal notice the next morning. Mara had written it carefully, identifying the specific authorization, stating that I disputed the signature and had not approved the proposed commitment, and requesting that the institution verify the documents before proceeding. She attached identifying information through the lender’s designated secure process and asked that relevant application records be retained. The letter did not accuse my father of a criminal offense. It established that the lender could not safely assume my participation was authorized merely because a document bore my name.
Later that day, a representative from the lender’s verification department called Mara. I joined the conversation after my identity was confirmed. The representative asked several direct questions about my relationship with the construction company and the financial support I had previously provided. I answered truthfully. Yes, I had helped the business during earlier difficulties. Yes, I had signed documents in the past. No, I had not authorized the new funding commitment. No, I had not agreed to serve as a guarantor for the proposed refinancing.
The representative then asked whether I had attended a meeting with my father concerning the application three months earlier. I said I had not. She explained that the lender’s file contained a reference to a family financial planning discussion at which my support had supposedly been confirmed. I searched my calendar while we were speaking. On the date in question, I had been attending an out-of-town client workshop. I had travel receipts, hotel confirmations, and work correspondence documenting where I was. Mara asked me to preserve those records and said we would provide them through the appropriate channel.
After the call, I remained seated at my desk for several minutes. The disputed signature was troubling enough, but the reference to a meeting I had never attended suggested that the lender had been given a fuller account of my involvement than I knew anything about. It was possible the description had been careless or mistaken. Still, someone had apparently presented my support as the outcome of a conversation that had not taken place. The problem could no longer be reduced to a single questionable signature.
Rachel joined Mara and me for another meeting that Friday. She had found a pattern in the materials connected to the company’s financial projections. Several expected contributions attributed to me corresponded to dates when my father had asked for money but received no explicit agreement. In the lender’s presentation, those uncertain amounts appeared under confirmed sources of financial support. Rachel explained that forecasting future help was one thing; representing it as committed funding was another. The distinction could materially affect a lender’s assessment of risk.
We also reviewed the way the company had described its financial condition. My father had repeatedly told me that the business was recovering, yet the refinancing materials suggested that cash shortages remained substantial. Some creditors had been paid through new borrowing or outside contributions rather than operating income. Rachel could not yet conclude whether that resulted from poor management, unrealistic forecasts, or deliberate misrepresentation. She did say that the business appeared more dependent on continued financial support than my father had admitted.
I asked whether the company was actually in danger of failing. Rachel looked at the figures before answering. It had real contracts, equipment, employees, and receivables. It was not an imaginary business built solely to extract money from me. But its liquidity was strained, and its commitments appeared to be growing faster than its dependable resources. Refinancing might temporarily relieve that pressure, depending on the terms, but it would not correct the underlying problems. If the application overstated available support, the new loan could make an unstable situation worse.
That distinction mattered to me. I had spent years worrying that withdrawing my assistance would destroy something my father had worked hard to build. Hearing Rachel describe the business without anger or sentiment helped me see that the company’s future depended on more than another transfer from my savings. It needed accurate accounting, realistic spending, and a management plan that did not assume I would rescue every shortage. My father might have understood construction better than I ever would, but his approach to financing had become increasingly dangerous.
On Saturday afternoon, my mother appeared at my apartment building without calling first. The security desk contacted me because she was insisting that I come downstairs. I found her in the lobby wearing a pale coat and carrying the same cream-colored handbag. She looked tired, with shadows beneath her eyes that makeup had not concealed. For a moment, she reminded me of the mother who used to wait outside school when I stayed late for activities. Then she asked whether I had contacted the lender to interfere with my father’s business.
I told her I had notified the lender that a document bearing my name was not authorized. She lowered her voice and said my father had been furious when he discovered the institution wanted additional verification. I asked whether she knew about the funding agreement. She looked toward the glass entrance doors and said she did not understand the technical details. I showed her a printed copy of the authorization. Her eyes moved over the page, and for a fraction of a second her expression changed. Then she said my father had handled all the business paperwork.
I asked whether she recognized the signature. She hesitated before saying it looked like mine. I told her that it was almost identical to one on a release signed years earlier. Her fingers tightened around the handbag. She said I was imagining something sinister because I was angry. I asked her directly whether she had ever seen my father use old paperwork to prepare a new application. She did not answer. Instead, she told me that a family should not destroy itself over a signature when there were employees whose livelihoods depended on the company’s survival.
I felt the familiar pull of guilt, but I was beginning to recognize when concern for other people was being used to avoid a difficult question. I told my mother that those employees deserved honest financial records and a lender who understood what it was being asked to finance. I would not allow my name to be used without consent simply to protect the company’s appearance. She looked genuinely frightened then. She said my father had worked too hard to lose everything. I replied that he still had an opportunity to explain what had happened.
Before leaving, she asked me to promise that I would not make a formal complaint. I told her I could not promise that without knowing the facts. She said I had changed, and this time there was little anger in her voice. I told her I had stopped accepting explanations that required me to ignore evidence. She stared at me for several seconds, then turned toward the entrance. Through the glass, I watched her walk to her car without looking back. I remained in the lobby, troubled less by her accusation than by the fear I had seen when she examined the signature.
That evening, Rachel sent me a copy of the comparison she had prepared between the original release and the disputed authorization. She had not attempted to offer a forensic handwriting conclusion. Instead, she highlighted the matching signature image, the date inconsistencies, and the financial representations that required independent verification. She also identified the old scanned release as a likely source worth examining. Mara was arranging a qualified document review and had requested that the lender retain any original electronic submissions.
I was reading Rachel’s notes when a new email arrived from the lender’s verification department. It confirmed receipt of our dispute and requested additional supporting records. Attached was a copy of the version of the funding authorization that had been submitted with the refinancing application. I opened it beside the copy supplied by my father’s office. The signature looked identical, but another detail caught my attention. Beneath my printed name was an acknowledgment that I had reviewed the company’s proposed obligations and agreed to be contacted for verification.
I had never received that contact. I had never reviewed those obligations. And the email address listed beside my name was not my email address. It was a similar-looking account using my first and last name with an extra character that could easily be overlooked. I checked the lender’s correspondence again. The supposed confirmation notices had been directed to that unfamiliar address. Someone had not merely submitted a document bearing my signature. The application contained contact information that could have allowed another person to receive communications intended for me.
I sent the discovery to Mara immediately. She called within minutes and asked me not to attempt to access the account or contact whoever controlled it. The information needed to be preserved and examined through proper procedures. After we ended the call, I sat at my kitchen table with both copies of the authorization open on the screen. The unexplained signature had raised the possibility of an unauthorized financial commitment. The false contact information suggested a deliberate effort to make that commitment appear verified without my knowledge. Whatever had happened, someone had taken considerable care to keep me outside the process.
END PART 5
PART 6 TITLE: The False Email Address Led to a Refinancing Application, and the Company’s Own Records Exposed What My Father Had Concealed
The unfamiliar email address remained on my mind throughout Sunday. It was close enough to mine that someone glancing quickly at a document might never notice the difference. The added character sat between two letters in my surname, making the address look like an ordinary variation rather than an obvious impersonation. I kept imagining routine lender messages arriving there: requests for confirmation, revised agreements, notices about additional documents. Whoever controlled the account could potentially receive information intended for me while leaving my actual inbox untouched.
Mara contacted the lender’s verification department first thing Monday morning. She explained the discrepancy, identified my correct contact information, and requested that the institution preserve records associated with the questionable address. The lender would not disclose account ownership or internal findings to us without following its procedures. It did confirm that the discrepancy had been added to its review. Mara warned me not to draw conclusions about who had created the address. Even when circumstances seemed to point toward an obvious person, the evidence needed to be collected without contaminating the inquiry.
Rachel approached the problem from another direction. She wanted to understand why the refinancing application relied so heavily on my supposed participation. The documents described a proposal to consolidate company obligations, obtain additional working capital, and reassure lenders about the business’s ability to meet future payments. On paper, the plan sounded like a reasonable response to a difficult financial period. The trouble was that several important assumptions depended on money I had not promised and on projections that Rachel could not reconcile with the records available to us.
She spread the company statements across the conference table and began explaining the differences. The business had several legitimate sources of revenue, including construction contracts already underway. Payments from customers arrived unevenly, which could create real cash shortages in an industry where wages, materials, and equipment expenses were due long before some invoices were collected. But that was only part of the problem. The forecasts also anticipated substantial contributions from outside sources that had not been independently confirmed. When those contributions were removed, the company’s available cash appeared considerably weaker.
I asked how long the situation had been developing. Rachel pointed to a sequence of statements covering more than two years. The company had repeatedly postponed certain payments while continuing to take on operating costs. Some new commitments were justified by expected contracts, but the timing of actual receipts did not always match the forecasts. My father’s optimistic descriptions of upcoming projects had obscured the financial gap between winning work and getting paid for it. The business was active, but activity was not the same as financial stability.
The most difficult discovery involved transactions that appeared to have little connection with construction. In the accounting records we had received, Rachel found payments to vendors associated with personal travel, entertaining, and expensive household services. Some might have represented legitimate business expenses, and she refused to classify them without invoices and explanations. Others were charged to accounts identified as company accounts but carried descriptions that suggested personal use. She highlighted the entries and requested supporting documentation through Mara rather than making assumptions based on merchant names alone.
I recognized one vendor immediately. It was the company that had installed custom fixtures during my parents’ kitchen renovation. My mother had shown me the finished work with enormous pride, describing it as something she and my father had saved for over several years. Yet the construction company’s accounts contained payments to the same supplier during the renovation period. That did not prove the company had paid for the household work. Contractors sometimes used the same suppliers for professional and personal projects. But the coincidence deserved examination.
Rachel asked whether I had records of the renovation. I searched old messages and found photographs my mother had sent while the work was underway. One showed newly installed cabinets. Another showed stone countertops covered with protective paper. In a third, my father stood beside a contractor, holding a folder with the supplier’s name printed on the front. I forwarded the images to Rachel, who added them to her reference materials. She explained that photographs could establish context and timing but not substitute for payment records or invoices.
The investigation was becoming more personal than I had expected. I could handle spreadsheets, contracts, and questionable forecasts. It was harder to look at photographs of family celebrations and wonder whether the money behind them had come from business resources, my personal accounts, or borrowing that the company could not afford. I remembered my mother showing off the renovated kitchen during a holiday dinner while my father complained that suppliers were demanding payment too quickly. At the time, I had treated those events as unrelated. Now I wanted to know whether they belonged to the same financial story.
The next morning, Mara arranged a meeting with Rachel and me to establish a consistent response. We agreed that the disputed authorization, the questionable email address, and the financial discrepancies should be treated as related concerns requiring separate verification. The lender would review the submitted documents. Rachel would continue identifying transactions that needed explanation. Mara would coordinate communication and determine what formal notices or complaints were appropriate. I would preserve my records and avoid direct arguments about wrongdoing with family members who had already shown little willingness to discuss facts calmly.
My father complicated that plan before lunchtime. He sent a long email accusing me of deliberately creating doubts about his company’s financial position. He said the lender had begun requesting additional information and that the refinancing process could be delayed. According to him, any resulting damage would be my responsibility. He reminded me that he had spent decades building the business and that I had no right to interfere simply because I was angry about a family disagreement. He ended by demanding that I withdraw my concerns immediately.
I read the email aloud to Mara during a brief telephone call. She asked whether he had addressed the unauthorized signature or incorrect email address. He had not. She advised me not to withdraw a factual dispute merely because someone disliked the consequences of verification. A lender needed accurate information when evaluating a substantial financial commitment. I understood that intellectually, but my father’s message still disturbed me. He knew exactly how to frame his problems in terms of responsibilities I had once been eager to shoulder.
I drafted a reply explaining that I had reported specific discrepancies and would correct any mistake if reliable evidence showed my concerns were unfounded. I also asked him to identify any document in which I had personally approved the refinancing. I sent the message through Mara’s recommended channel and returned to work. Several hours passed without an answer. Then Madison called from an unfamiliar number. I answered before realizing who it was, and her voice emerged sharp and breathless. She said I needed to stop attacking Dad before he lost the company.
I asked Madison what she knew about the refinancing. She said she understood enough to know that I was causing trouble. I asked whether our father had shown her any of the documents. She hesitated, then said he had explained that I was refusing to honor commitments I had previously made. I told her I had never approved the new funding arrangement. She dismissed the distinction, saying that I had always helped Dad when he needed money. I reminded her that the same reasoning had led her to attempt a luxury purchase using a card I had canceled.
She became angry at the comparison. She said the boutique incident had nothing to do with the construction company and accused me of deliberately mixing unrelated matters to make the family look dishonest. I agreed that the matters were different. Her shopping attempt involved access to my personal credit card. The refinancing involved documents that appeared to represent my consent to a business transaction. What connected them was the assumption that my permission could be ignored. Madison went quiet for several seconds, then asked whether I intended to report Dad to the authorities.
I told her I intended to establish who had created and submitted the disputed documents. If the evidence showed wrongdoing, I would not conceal it. Madison said I was willing to destroy our father over a piece of paper. I asked whether she understood what it meant for someone to sign my name to a financial authorization without my knowledge. She replied that families sometimes handled paperwork for one another. I told her there was a difference between helping someone complete a form and falsely representing their agreement to provide money.
Before hanging up, Madison said something unexpected. She asked whether the lender had contacted me about a confirmation email. I stopped moving. Until then, I had not told her about the questionable address or the verification messages. I asked what email she meant. She said Dad had mentioned a problem with the lender’s correspondence and that everyone was becoming unnecessarily suspicious. I asked whether she had seen the address used in the application. Her answer came too quickly. She said she had no idea what address I was talking about.
After the call, I wrote down the exchange and sent the note to Mara. I did not want to assume Madison was involved simply because she knew about a verification issue. My father might have told her everything after receiving questions from the lender. Still, her knowledge suggested that the family had been discussing the application more extensively than anyone admitted. The more I examined the situation, the clearer it became that several people knew pieces of the truth while continuing to insist that I should remain uninformed.
Rachel’s next findings arrived that afternoon. She had compared the accounting records with the limited bank statements available and identified a series of transfers from company accounts into an account used for household expenses. Some transactions were labeled as owner distributions. Others carried vague descriptions such as reimbursement or administrative costs. Rachel explained that owner distributions were not inherently improper, particularly if correctly recorded and legally permissible. What mattered was whether the amounts matched the company’s financial statements and whether the refinancing application accurately reflected the resulting cash position.
One transfer stood out because of its timing. It had been made shortly before my father asked me to cover an urgent payment to a supplier. The amount leaving the company was substantial, and the supplier later received money from an account funded partly by one of my transfers. Rachel did not claim the two transactions were directly connected. Without fuller records, it was impossible to trace every dollar conclusively. Nevertheless, the sequence raised an important question: why had funds been moved out of a financially strained business shortly before I was told that the company could not meet an essential obligation?
I remembered the conversation surrounding that particular request. My father had called late in the evening, his voice tense, saying a supplier was threatening to halt deliveries. He told me employees would be sent home if materials did not arrive. I had transferred the money the next morning without asking to see the full accounts. My father’s relief sounded genuine. He thanked me and promised repayment as soon as several customer invoices cleared. Months passed. The repayment never arrived, and I had not pursued it because another crisis had taken its place.
Rachel advised caution. A business owner might have legitimate reasons for moving funds between accounts, and the available statements did not establish the full purpose of the transfer. But the transaction needed documentation. We added it to a schedule of questions for the company. I found myself hoping there would be a straightforward explanation. I did not want every memory of helping my father to become evidence that he had exploited my trust. Some of those early emergencies had been real. I still believed that. The difficulty was determining when his reliance on me had crossed the line into concealment.
Two days later, the company’s administrator called from her personal phone. She said she was uncomfortable with the tension surrounding the refinancing and wanted to clarify that she had not prepared the disputed authorization. I told her she did not need to discuss anything that placed her in a difficult position at work. She replied that she was worried her name might appear on a document routing record because she had scanned the original release years earlier. She remembered doing so because my father had asked her to preserve complete copies of several financing documents.
I asked whether she had seen the newer authorization before it appeared in the refinancing packet. She said she had first encountered it while organizing files requested by the lender. The document was already in the application folder. She did not know who created it or who added the signature. She also mentioned that my father had instructed office staff to direct most refinancing questions to him personally rather than contacting outside parties. I thanked her for clarifying what she knew and encouraged her to preserve any relevant workplace records through appropriate channels.
After the call, I felt the strange exhaustion that comes from learning something important without knowing what it proves. The administrator’s account supported the possibility that the older scanned release was available within the office. It did not establish who had used it or whether the new signature was copied from that file. Mara wanted the original electronic records examined before anyone made that accusation. I agreed. I had spent years accepting my father’s statements without evidence. I did not want to answer that mistake by making accusations based only on suspicion.
On Friday morning, Mara informed me that the lender had requested additional verification from the company. The refinancing had not yet been finalized, and the institution was reviewing discrepancies raised by our notice. No final determination had been communicated. Mara explained that the lender might suspend the review, require new documents, or take other action depending on what its internal investigation found. She could not predict the outcome. What she could say was that my father’s assurances were no longer being accepted without verification.
My mother called that evening, sounding more anxious than angry. She said the construction company was having difficulty with several payments and that my father feared employees might lose their jobs if the refinancing stalled. I told her I was concerned about the employees as well. Then I asked whether she believed it was fair to obtain financing based on documents I had not signed. She said she did not know who had prepared the paperwork. I asked whether my father had explained the unfamiliar email address. Her silence lasted long enough to tell me she understood why the question mattered.
Finally, she said she had seen Madison helping my father organize computer files several months earlier. She insisted that this was ordinary family assistance and did not mean Madison had done anything improper. I asked whether she remembered what they were working on. My mother said the dining room table had been covered with folders, invoices, and copies of old agreements. Madison had been using her laptop while my father dictated information. My mother had assumed they were preparing documents for the refinancing. She had not asked questions because, as she put it, financial matters were always your father’s responsibility.
I listened without interrupting. Madison had known about the confirmation email, and now my mother remembered her helping prepare paperwork around the relevant time. Neither fact proved she had created the disputed address or handled my signature. Still, the possibility that she had participated in preparing the application made her earlier insistence that she knew nothing difficult to accept. I asked my mother whether she would be willing to describe what she remembered accurately if the lender or an investigator contacted her. She sounded frightened, then said she did not want to take sides between her daughters.
I told her that telling the truth was not the same as choosing a side. She began crying, saying everything had become unbearable and that she wished we could return to the way things had been before the argument. I thought about the money, the boutique, the documents, and the increasingly strained company accounts. Returning to the old arrangement would not make those facts disappear. It would merely allow everyone to avoid confronting them. I told her I loved her, but that I could not restore a situation built on silence.
After the call, I sent Mara a careful account of what my mother had said. I included the distinction between what she claimed to have seen and what she merely assumed. Rachel received a copy because the timing of Madison’s involvement might help establish how the application materials were assembled. Neither woman reacted dramatically. Mara said the information was relevant but incomplete. Rachel updated the document timeline. Their discipline was reassuring. I was beginning to understand that a sound investigation moved forward by testing explanations, not by selecting the most emotionally satisfying one.
The next morning, Rachel called with a development from the records review. She had located an inconsistency between the company’s accounting summaries and the financial position described in the refinancing materials. The application appeared to treat certain anticipated outside contributions as if they were already committed, while the internal records described them as expected assistance. Without those amounts, the company’s projected ability to service the proposed refinancing was significantly weaker. Rachel believed the discrepancy was material enough to require a formal accounting analysis for the lender.
I asked what that would mean for my father. She said the lender needed to understand the true position before making a decision. A revised forecast might show that the company could still support a smaller transaction, or it might reveal that refinancing was not viable on the proposed terms. The answer depended on verified numbers. She reminded me that the purpose of the review was not to punish the business. It was to prevent decisions based on financial information that could not be substantiated.
That evening, I received a short message from my father. He said he had heard I was examining his company’s accounts and demanded to know whether I intended to take control of the business. I stared at the question in disbelief. I had never sought ownership, a management position, or access to company property. I wanted to establish whether my name had been used without consent and whether the financial representations involving me were accurate. Yet my father seemed determined to interpret every request for evidence as a challenge to his authority.
I replied that I had no intention of taking his company. I wanted the disputed authorization withdrawn, my name removed from any unsupported financial commitment, and the company’s obligations represented accurately. He responded that I would never understand what it meant to build something from nothing. Then he wrote that he would not allow his own daughter to destroy his life’s work. I looked at the message for a long time. He had stopped arguing about the signature or the refinancing figures. He was beginning to tell a different story, one in which I was the aggressor and he was defending himself.
END PART 6
PART 7 TITLE: My Father’s Story Changed from Financial Trouble to Betrayal, Just as the Lender Began Questioning the Documents Submitted in My Name
My father’s accusation arrived while Rachel was preparing the final version of her accounting report. I read his message twice, trying to understand how a request to correct unauthorized financial information had become an attempt to seize his company. He had spent years insisting that the business belonged to him and that I had no right to question its decisions. Now he was suggesting I wanted ownership simply because I refused to keep funding it. The contradiction might have been absurd if the consequences had not been so serious.
Rachel had taken over a conference room at Mara’s office for the morning. The table was covered with statements, transaction schedules, and copies of the refinancing application. She was reviewing each finding against its supporting document, marking uncertainties wherever the available evidence was incomplete. I watched her work and wondered how my father would describe the same records. To him, every question was an insult. To Rachel, an unexplained entry was simply an entry that needed further examination. I was learning how much damage could be done when pride replaced accountability.
The report did not present every unusual transaction as misconduct. Rachel separated confirmed facts from matters requiring additional records. She identified discrepancies between the company’s internal forecasts and the funding commitments described to the lender. She also documented transfers that appeared inconsistent with the company’s explanations of its financial difficulties. Several expenses potentially benefited my parents personally, although the available records were insufficient to establish their proper accounting treatment. Her conclusions were restrained, which made them harder to dismiss.
When I asked whether the business could survive without my additional money, she pointed to the current obligations. It had valuable equipment, established customer relationships, and work that could generate future revenue. It also had substantial payment pressures and a financing strategy that relied on assumptions not yet supported by documentation. Survival was possible, she said, but it would require difficult decisions: reducing unnecessary spending, negotiating with creditors, collecting outstanding invoices, and establishing realistic cash-flow projections. Another unexamined contribution from me would postpone those choices rather than eliminate them.
I thought about the construction company as it had been when I was young. My father sometimes took me to job sites on Saturday mornings. I remembered the smell of wet cement, the metallic noise of tools, and the pride in his voice when he pointed toward a building and explained what his crew had accomplished. He knew every foreman by name. Employees brought their children to company picnics. There had been a time when my father’s pride came from doing difficult work well. Somewhere along the way, protecting the appearance of success had become almost as important as the work itself.
Mara joined us after lunch to discuss how the report should be submitted. We needed to distinguish my personal financial dispute from the company’s broader accounting issues. I had standing to challenge representations made about my own authorization, but that did not give me unrestricted rights to every confidential company record. Rachel’s analysis would therefore identify the documents she had reviewed, their sources, and the limitations of her conclusions. Mara would transmit the material through the lender’s designated channels and determine whether a separate complaint was warranted.
I asked whether the authorities would automatically investigate my father once the report was submitted. Mara said no. A complaint could be reviewed, rejected, referred elsewhere, or investigated further depending on the evidence and applicable procedures. The lender also had its own internal obligations and safeguards. I would not control either process. My responsibility was to provide accurate information and avoid concealing anything material. She looked at me carefully when she said that. I understood she was warning me not to confuse accountability with revenge.
That evening, Madison sent me a message accusing Rachel of being someone I had hired to manufacture accusations. I had not told Madison Rachel’s name, although my father might have learned it through the company’s correspondence. I asked what evidence she had that Rachel’s work was inaccurate. Madison responded that accountants could make numbers say anything. I reminded her that the report cited records and requested missing documentation rather than assuming guilt. She said none of that mattered because I was choosing outsiders over my own family.
I asked whether she had helped prepare the refinancing paperwork. She read the message but did not answer for nearly an hour. Then she replied that she had helped Dad with ordinary office tasks and that there was nothing suspicious about that. I asked whether she had created or used an email address resembling mine. Her next response was angry and evasive. She said I was treating everyone like a suspect and that she would no longer participate in my interrogation. I saved the exchange and did not pursue it further.
The next day, I received a call from a relative I had not spoken with in several months. My aunt Patricia, my father’s older sister, sounded concerned. She said my father had told her the family was experiencing a disagreement over the company and that I was attempting to interfere with its refinancing. According to his version, I had provided substantial funding over the years and now wanted authority over the business in return. Patricia asked whether that was true. I told her I had never demanded ownership or management control.
She listened while I explained that a document bearing my signature had been submitted without my authorization. I did not provide private financial details or accuse anyone of a crime. I said the lender was reviewing the matter and that I wanted my name removed from commitments I had not made. Patricia was quiet for a moment, then asked whether my father knew I disputed the signature. I told her he had known for some time. She sighed and said he had described the matter as a daughter trying to exploit a business crisis.
I could hear how uncomfortable she was. Patricia had known my father all her life and understood his pride better than almost anyone. She said he sometimes became impossible when he believed his authority was threatened. I asked whether he had told her about ordering me out of the house. He had mentioned an argument, she said, but nothing about throwing my suitcase down the stairs. I explained what happened, including Madison’s demand for the credit card. Patricia did not interrupt. When I finished, she said she was beginning to understand why the disagreement had lasted so long.
I ended the call feeling unsettled. My father had started telling relatives a version of events in which the disputed documents disappeared and my financial support became a claim to ownership. I knew how persuasive he could be. He had spent decades negotiating contracts and reassuring clients when projects became difficult. He could sound reasonable even while omitting the facts that changed the meaning of a story. I decided not to begin calling relatives in an effort to defend myself. The documents would need to speak more clearly than competing family accounts.
On Thursday, Mara informed me that the lender had requested a formal statement concerning the disputed authorization. We prepared it together. I described the original financing documents I had signed years earlier, the newer authorization I had never approved, the unfamiliar email address, and the steps I took after discovering the discrepancy. I included records showing I was out of town on the date of the alleged confirmation meeting. Every statement was supported where possible. Where I did not know something, I said so.
Signing that declaration felt different from signing the countless forms I had completed for my father over the years. I read each sentence carefully, asked questions about unfamiliar language, and verified every attachment before authorizing its submission. The process reminded me that my signature was not merely a convenient mark someone could reproduce. It represented a decision, an acknowledgment, or an obligation that belonged to me alone. I had been careless about that distinction in the past because I trusted the people requesting my help.
Rachel completed her accounting report the following morning. Before sending it to Mara, she asked me to review the factual descriptions of my own transfers. I found two dates that needed clarification and one payment I remembered differently from its bank description. Rachel corrected the timeline and added a note explaining the uncertainty. I appreciated that she did not treat my memory as infallible simply because I was her client. The purpose of the report was to establish what could be verified, not to produce the most damaging possible account of my father’s decisions.
One section particularly troubled me. The refinancing projections assumed that I would provide financial support sufficient to cover a significant portion of anticipated shortfalls. Without that assumed contribution, the company’s capacity to meet its obligations looked markedly different. Rachel had tested the numbers under both scenarios. The difference was not cosmetic. It affected whether the proposed financing appeared sustainable. I finally understood why my father was so desperate for me to confirm the arrangement. My supposed commitment had become a central part of the picture presented to the lender.
That evening, my mother called and asked whether I would consider attending a family dinner over the weekend. She said my father wanted everyone together and that relatives were beginning to worry about the dispute. I asked whether he intended to discuss the authorization. She said he wanted to explain his position and hoped I would listen respectfully. I told her I would not agree to a meeting designed to pressure me into withdrawing a documented concern. She replied that I had become suspicious of every gesture the family made.
I wanted to believe the invitation was sincere. My mother sounded tired and embarrassed, and I knew she hated open conflict. But she had repeatedly asked me to restore financial access without acknowledging why it had been withdrawn. I told her I would consider a meeting once we understood its purpose and who would attend. She said that was unnecessarily formal. I reminded her that the last informal discussion at their house had ended with my belongings thrown down the staircase. She did not argue with that.
On Saturday morning, an unexpected message arrived from the company’s administrator. She had located the earlier release that I had signed six years before, along with a record indicating when it had been scanned into the office archive. The document was exactly as I remembered. She had also found a later internal file reference showing that a copy had been accessed during preparation of the refinancing materials. The record did not identify who had used the signature or establish how the disputed authorization was produced. It did, however, connect the old document to the preparation period.
I forwarded the information to Mara and Rachel. Mara said it strengthened the reason for independent document examination but did not settle the question of responsibility. Rachel added the reference to her chronology. I sat looking at the two signatures afterward, wondering what my father would say if asked directly how they had become so similar. I had already asked him to produce evidence of my authorization. He had responded with accusations about loyalty and ownership. Each refusal made the absence of an ordinary explanation harder to ignore.
By Sunday, my father’s messages had become noticeably different. Instead of demanding immediate money, he warned that I could face consequences for damaging the company’s reputation. He said suppliers were becoming nervous and that the refinancing delays were creating uncertainty. I understood his concern, but the implication was troubling. He wanted me to accept responsibility for the consequences of questions the lender had a duty to examine. I replied that the most effective way to resolve the matter was to provide accurate documents and cooperate with verification.
He answered that he would not be threatened by his own daughter. I put the phone aside and went for a long walk. The air was cool, and fallen leaves collected along the edges of the pavement. I passed a family leaving a restaurant, two children arguing over who would carry a paper bag while their parents laughed. The ordinary affection between them made my chest ache. I missed being part of a family that could spend an afternoon together without discussing what I owed anyone. I wondered whether that family had ever truly existed or whether I had remembered it selectively.
On Monday morning, Mara received acknowledgment that the lender had accepted our additional documentation for review. Its verification and risk teams were examining the disputed authorization, the contact information, and the financial representations associated with my supposed support. She cautioned me that the lender had not issued a final finding and that its internal process could require more evidence. I understood. Still, having the information formally acknowledged felt important. The matter no longer depended on persuading my father to admit that a problem existed.
Rachel called later that day to review a final question about the accounting report. She wanted to confirm that one of my transfers had been made directly to the company rather than to my father’s personal account. I checked the bank confirmation and verified the recipient. She thanked me and said the distinction would be reflected in the final schedule. I asked whether she thought my father understood the seriousness of the situation. She said she could not know what he believed, but the documents suggested he had relied on assumptions that could not be substantiated.
The following afternoon, I received an unfamiliar call from a woman identifying herself as a representative handling concerns associated with the lender’s application records. She did not share details of the institution’s internal investigation. She verified that my complaint was being reviewed and explained how to provide additional evidence if necessary. I gave her Mara’s contact information and requested that formal questions be directed through counsel. After we ended the call, I felt unexpectedly nervous. I had wanted an independent review, but hearing that the process was moving forward made the conflict feel more permanent.
My mother sent a message that night saying my father had been pacing the house and complaining that everyone was turning against him. Madison had apparently been helping him organize records again. I asked whether they were preparing documents for the lender. My mother replied that she did not know. Then she wrote that I had no idea how much pressure he was under. I looked at the message and thought about all the years I had used the same pressure as a reason not to ask questions. His distress might be genuine, but it could no longer determine whether I told the truth.
On Wednesday, Rachel called while I was working late. Her voice was steady, but I could hear papers moving on her desk. She told me that the lender had received our documentation and was suspending its refinancing review while the discrepancies were examined. I asked whether that meant the application had been rejected. She said no. A suspension was not a final decision. It meant the lender was not proceeding on the existing basis until the relevant issues were resolved. I wrote down the distinction because I knew my father would likely describe it differently.
I asked about the accounting report. Rachel confirmed that it had been delivered through the appropriate process to the lender’s fraud review team, with its supporting schedules and limitations clearly identified. She also said the investigators handling our separate complaint had acknowledged receipt of the information. Neither acknowledgment established wrongdoing, and she reminded me that conclusions would depend on further examination. I listened, watching rain begin to strike the windows of my office. The information was sobering, but it was also the first clear evidence that someone outside the family was examining the facts.
Then Rachel told me something that made me straighten in my chair. My father had called an emergency family meeting for the following evening. He had contacted several relatives, telling them I was attempting to take control of his company and that he needed their support. Patricia had informed Rachel through Mara because she was concerned about how the situation was being represented. I asked whether the meeting would be at my parents’ house. Rachel said yes. My father had invited everyone except me, apparently intending to discuss my conduct in my absence.
I looked out at the rain for several seconds. My father had already thrown me out, questioned my loyalty, and attempted to use my financial history as evidence against me. Now he wanted to gather the family and describe my efforts to verify an unauthorized document as an attempt to steal his business. I could almost hear him standing in the living room, telling everyone that he had given his daughter everything and that she was repaying him with betrayal. This time, however, I had records that could be checked.
I asked Rachel to tell Mara I wanted to attend. I would not arrive without notice or bring confidential lender information into a room full of relatives, but I was prepared to answer factual accusations about my own conduct. Rachel asked whether I thought my father would allow me to speak. I said I did not know. Then I looked at the disputed authorization lying beside my keyboard and made a decision. I would go, not to beg for my place in the family, but to refuse the false story being told in my name.
END PART 7
PART 8 TITLE: At the Emergency Family Meeting, My Father Accused Me of Stealing His Company Until the Evidence Turned the Room Against His Story
The next evening, I parked two houses away from my parents’ property and sat behind the steering wheel for several minutes. The windows glowed warmly against the darkening street. Cars crowded the driveway, and I recognized my aunt Patricia’s blue sedan near the mailbox. Through the front windows, I could see people moving around the living room. It looked like one of the large family gatherings my mother used to organize during the holidays. The difference was that this time I was apparently the subject of the conversation rather than a welcome guest.
Mara had advised me to keep the meeting focused on correcting factual statements about myself. I carried a slim folder containing copies of my original financial notices, the disputed authorization, and a short chronology of the events. I did not bring the full accounting report or confidential documents belonging to the lender. If anyone wanted to understand the formal review, they could be told where the relevant questions stood without being given material they had no right to examine. Rachel had helped me prepare a one-page summary distinguishing verified facts from unresolved allegations.
I walked up the front path and rang the bell. My mother opened the door almost immediately. She stared at me, her hand still gripping the brass handle. Behind her, I heard my father’s voice rising from the living room. My mother whispered that I had not been invited. I told her Patricia had said I could come to address the accusations being made about me. She looked over her shoulder, visibly torn between stopping me and avoiding another confrontation at the entrance. Then she stepped aside.
The foyer looked exactly as it had the night I left. The marble staircase curved toward the upper floor, and the small cabinet near the front door still stood against the wall. I remembered my suitcase striking the steps and its broken wheel disappearing beneath the cabinet. I had spent weeks replaying that moment. Now, standing there again, I felt a sharp recognition rather than the helplessness I had experienced before. I knew where the exits were. I had driven myself. I could leave whenever I chose.
My father was standing near the fireplace when I entered the living room. Patricia sat in an armchair, and several uncles, cousins, and older family friends occupied the sofas. Madison stood beside the dining room entrance with her phone in her hand. The conversation stopped as soon as everyone noticed me. My father looked surprised for an instant, then angry. He demanded to know why I had come when I was clearly not wanted. I told him I had heard he was discussing allegations about me and thought it reasonable that I be present.
Patricia stood before he could answer. She said she had invited me because she did not believe a family should gather to judge someone who had no opportunity to explain herself. My father told her that she did not understand the situation. Patricia replied that she understood enough to want both sides heard. Her voice was calm, but I recognized the stubbornness she and my father shared. He stared at her, then gestured toward an empty chair. I sat down and placed my folder on my lap.
My father began by describing the sacrifices he had made while building the construction company. He spoke about difficult contracts, employees who depended on him, and years of physical work. Those things were real, and I did not challenge them. Then he said that when the business began facing financial pressure, I had offered help but later demanded control over its finances. According to him, I was now using lawyers and accountants to interfere with refinancing because I wanted influence he had refused to give me.
I waited until he finished. Then I asked one question. Had I ever requested ownership of the company? He said my demands for financial records amounted to the same thing. I asked whether I had requested a management position, shares, or authority to sign contracts. He replied that I was trying to force him into submission through outside investigators. I looked toward Patricia and the others. “I asked for records concerning money attributed to me,” I said. “That isn’t the same as asking to own the business.”
My father dismissed the distinction. He said I had contributed to the company willingly for years and was now pretending those contributions were evidence of wrongdoing. I agreed that many of my earlier payments had been voluntary. I explained that I had helped when suppliers were overdue and employees needed wages because I wanted the company to survive. I was not seeking to recover every gift or rewrite every arrangement as a loan. What I disputed was a newer commitment that had been presented as authorized even though I had never agreed to it.
I opened the folder and took out a copy of the funding authorization. I held it up long enough for the people nearest me to see what I was discussing. I explained that a document bearing my signature had been submitted as part of a proposed refinancing arrangement. The signature appeared almost identical to one on an older release I had genuinely signed. The application also included an email address resembling mine but not belonging to me. I had notified the lender because I could not confirm a commitment I had never made.
My father interrupted, saying I was deliberately exaggerating an administrative mistake. I asked whether he was saying the document had been submitted accidentally. He said the company had reused paperwork from earlier arrangements because my support had always been understood. I asked who had authorized the new commitment. He replied that I had made my intentions clear through years of helping. I told him past assistance did not constitute permission to sign a new agreement in my name. Several relatives shifted in their seats. The distinction was simple enough that no financial expertise was necessary.
Madison stepped forward and accused me of humiliating our father. She said he had been under enormous pressure and that I was treating ordinary family paperwork as though it were a criminal conspiracy. I asked whether she had helped prepare the refinancing application. Her expression tightened. She admitted that she had assisted with scanning documents and entering information, but insisted she had only followed instructions. My father told her not to discuss company matters in front of the family. The interruption made several people turn toward him.
Patricia asked why he was unwilling to explain how the document had been prepared. My father said the matter was being handled by the lender and that private financial affairs had no place in a family meeting. Patricia reminded him that he had called everyone together to accuse me of trying to steal the business. If he could discuss those accusations, she said, he could answer reasonable questions about their basis. My father looked around the room and seemed surprised that nobody immediately defended him. For years, his certainty had been enough to settle most disagreements.
My mother stood near the doorway, twisting the strap of her handbag. I asked whether she remembered seeing Madison and Dad organize old financing papers several months earlier. She looked at him before answering. Then she said yes, she remembered folders spread across the dining room table and Madison using her laptop. My father said that was entirely normal. I agreed. Preparing business documents was not inherently suspicious. The problem was that a document had emerged from that work appearing to carry an authorization I had never given.
I asked Madison about the unfamiliar email address. She looked down at her phone and said she had merely entered information she was given. I asked who had supplied the address. She said she could not remember. My father interrupted again, telling me to stop cross-examining my sister. I told him nobody had to answer a question they were uncomfortable discussing in that room, but the lender would still need to establish whether its verification information was accurate. I was not asking my family to reach a criminal verdict. I was asking them to stop pretending the discrepancy did not matter.
One of my uncles, Robert, asked whether the lender had already approved the refinancing. I explained that the review had been suspended while the institution examined the disputed materials. That did not mean the application was permanently rejected or that anyone had been found responsible for wrongdoing. My father seized on that distinction, saying I had admitted there was no proof of fraud. I agreed that no final finding had been made. Then I pointed out that uncertainty was precisely why independent verification was necessary.
Robert turned to my father and asked why the company had not contacted me directly before submitting documents that depended on my financial support. My father replied that he had tried, but I had become uncooperative after an argument with the family. I reminded him that the application referred to a confirmation meeting months before the argument. According to the document, I had attended and approved the arrangement. On that date, I had been away on business. I had already provided records establishing where I was. My father stared at me without responding.
I continued carefully. The question was not whether he believed I ought to support the company. The question was whether the lender had received accurate information about commitments I had actually made. I explained that the application used an unfamiliar email address for verification and that I had never received the notices apparently sent there. I also explained that the lender was examining the submitted records and that I intended to cooperate fully. My father called the entire process unnecessary. Patricia asked whether he would have considered it unnecessary if someone had used his signature without permission.
For several seconds, the room was silent. My father looked toward the fireplace rather than answering. Madison shifted her weight and glanced at my mother. I could hear the faint ticking of the clock above the mantel. It struck me that nobody had asked about the amount of money I had previously provided or accused me of refusing to help someone in immediate danger. The conversation had narrowed to a specific issue that could not be resolved through guilt. Either I had authorized the new commitment or I had not.
My father finally said he had never intended to harm me. The change in language was significant. He was no longer insisting that I had signed the authorization. He was speaking about intention. I asked whether he had known the lender’s documents presented my support as confirmed. He said the company needed financing and that he believed I would agree once I understood the situation. I told him that belief was not authorization. He replied that he had been trying to protect a business employing people who depended on him.
I believed that he feared losing the company. I also believed he had convinced himself that the seriousness of the financial situation justified decisions he would never tolerate from someone else. But none of that changed the facts. I told him the employees deserved accurate financial information, and lenders deserved to know which commitments were real. The company needed a credible plan, not a promise made in my name without asking me. My father stared at the carpet. He looked older than he had a month earlier.
Then Madison said quietly that she had not understood the full consequences of the paperwork. Everyone turned toward her. My father told her to stop speaking. She looked at him, visibly frightened, then said she had helped transfer information from older documents into the refinancing files because he had asked her to. She claimed she thought it was routine paperwork and had not realized that my signature could be interpreted as approval of a new obligation. I asked whether she had inserted the signature image. She said she had used a scanned file that Dad had given her.
The room seemed to contract around us. My father demanded that Madison stop discussing confidential business matters. Patricia told him to let her finish. Madison’s eyes filled with tears, and she said she had not meant to cause a problem. She explained that her father had told her the family had already agreed to continue supporting the company. Because I had helped so often before, she assumed the paperwork merely confirmed an existing arrangement. She did not claim to have witnessed me sign the new authorization. She had relied on what he told her.
I asked about the email address. Madison rubbed her hands together and admitted that she had entered a contact address into the application at my father’s request. She said he had provided the address and told her it was used for family financial correspondence. She had never checked whether it belonged to me. I did not know whether her account was complete, and I had no intention of deciding that question in front of the family. But her explanation was consistent with the possibility that the document and contact information had been assembled without involving me.
My mother sat down heavily on the sofa. She looked at Madison, then at my father. “You told me Emily had already agreed,” she said. He replied that he had every reason to expect my help. My mother shook her head. She reminded him that I had repeatedly asked for documentation before committing further money. He said those demands had come later, after the family argument. I told him the application referred to a meeting I had never attended and contained a signature I had never knowingly provided. Those discrepancies existed regardless of when our relationship deteriorated.
For the first time, my father seemed unable to find an answer that satisfied even himself. He said there had been confusion and that everyone was making a technical matter unnecessarily dramatic. Patricia asked whether he would correct the lender’s records. He said the lender was already reviewing them. Robert asked whether he would stop telling relatives that I was trying to steal the company. My father looked directly at me, then away. He did not apologize, but he also did not repeat the accusation.
I had imagined this meeting many times during the previous twenty-four hours. In some versions, my father admitted everything and asked me to forgive him. In others, he became so furious that I was forced to leave again. What actually happened was quieter and more uncomfortable. My relatives sat with the knowledge that his version of events had omitted important facts. Madison cried into a tissue while insisting she had only wanted to help. My mother stared at the handbag resting beside her. My father stood by the fireplace, his authority diminished not by an attack but by questions he could not answer.
I told the family that the lender and appropriate investigators would determine what the documents meant and whether anyone had violated the law. I would not use a family gathering as a substitute for that process. I also made clear that I would not assume financial responsibility for the refinancing simply because the company needed money. If the business required assistance, it would have to pursue legitimate arrangements supported by accurate information. My previous contributions did not give anyone permission to make new commitments on my behalf.
Patricia thanked me for coming. She said she wished the family had addressed the situation privately and honestly before it reached this point. I told her I had tried. I had brought financial statements to dinner, requested records, and offered to discuss the matter calmly. My father had thrown me out, and afterward the family had continued attempting to use my accounts. I did not say those things to humiliate him. I said them because the sequence mattered. This conflict had not begun with a lawyer’s letter. It had begun when my attempts to set limits were treated as disloyalty.
As the meeting broke apart, my mother followed me into the foyer. She looked toward the staircase, and I wondered whether she was remembering the same night I was. She told me she had not realized how much had happened behind the scenes. I asked whether she had really believed my father possessed permission to use my signature. She said she had wanted to believe him because the alternative was frightening. I understood that more than I wanted to. For years, I had accepted explanations that allowed me to avoid confronting what our family had become.
Madison approached us before I could leave. Her face was red from crying, and her voice sounded smaller than usual. She said she had saved copies of some of the refinancing files on her laptop because she had been helping organize them. I asked whether she had altered any of the originals. She shook her head and said she had only copied what her father gave her. She did not know what the lender might need, but she was willing to provide the materials through Mara rather than continue arguing about them.
I told her that preserving the original files and their records was important. She nodded. Then she asked whether I hated her. I looked at my younger sister and thought about the years of shopping requests, small manipulations, and casual assumptions that I would always pay. I was angry with her. I was disappointed, too. But hatred was not what I felt. I told her I needed honesty more than apologies designed to make the conversation end. She began to cry again, this time without trying to defend herself.
My father appeared at the end of the hallway while we were speaking. He told Madison to come upstairs and said the family had already discussed enough. She looked at him, then back at me. For a moment, I thought she would obey automatically. Instead, she said she would speak to Mara about preserving the files because she did not want anyone accusing her of destroying records. My father’s jaw tightened. He said she was allowing me to turn her against him. Madison answered that she was trying to protect herself by telling the truth.
I left before another argument could begin. Outside, the air was damp and cool, and the driveway lights cast long shadows across the pavement. My car was exactly where I had parked it. I sat behind the steering wheel and called Mara to describe what had happened, careful to separate the statements I had heard from what I could independently verify. She asked whether Madison had offered the electronic files voluntarily. I said yes. Mara explained that any transfer should be handled appropriately, with attention to company confidentiality and preservation of original evidence.
On the drive home, I realized I had not once asked my father to welcome me back. That had been the central fear haunting me since the night he threw my suitcase down the stairs. I had imagined that protecting my finances might cost me my family forever. The meeting had not resolved that question. My father remained angry, my mother was frightened, and Madison was struggling with the implications of her own involvement. But I no longer believed I could repair the relationship by returning to the arrangement that had damaged it.
When I reached my apartment, I found a message from Patricia thanking me for answering questions without turning the meeting into another shouting match. Beneath it was a message from Madison saying she had located the folder containing the refinancing drafts and was willing to discuss how to preserve the files. I forwarded the information to Mara. Then I noticed one final email, sent from my father’s personal account. Its subject was simply: We Need to Talk About the Original Agreement.
I opened the message expecting another demand or accusation. Instead, my father wrote that there were older documents relating to the money I had contributed years before, and that some of those records had not been included in the files I received. He said the original financial arrangements were more complicated than I understood. He wanted to discuss them privately before anyone else examined the documents. There was no apology and no explanation of the disputed signature. Yet his message suggested that the history of my support contained information he had deliberately withheld.
I sat at my kitchen table, reading the email beneath the light of a single lamp. The original rescue of the company had been the reason I continued helping for so many years. I remembered signing agreements, trusting promises, and believing my father when he said the business would eventually repay what I had advanced. Now he was acknowledging that records connected to those arrangements had been kept from me. I forwarded the message to Mara and asked her to request the documents formally. Whatever they contained, I was finished accepting my father’s recollection as the only available record of my own money.
END PART 8
PART 9 TITLE: The Agreement My Father Kept Hidden Revealed That He Had Not Only Used My Name but Tried to Erase What He Owed Me
The morning after the family meeting, I woke to an email from Mara containing a single question: Did your father ever give you a copy of the original repayment agreement? I sat up in bed and read it again. Seven years had passed since I first helped rescue his construction company, and I remembered signing several documents during those desperate weeks. Some concerned equipment financing. Others recorded money I had transferred directly into the business. But I could not remember receiving a complete agreement explaining how those advances would eventually be repaid.
I called Mara before getting dressed. She had reviewed my father’s latest message and found his reference to the original agreement significant. Until now, he had insisted that my contributions were ordinary family assistance, not transactions that required formal accounting. Suddenly, he was acknowledging the existence of documents I had not seen. Mara explained that those records might clarify whether certain transfers were gifts, loans, or something else entirely. She wanted to request complete copies through a formal written demand rather than rely on whatever my father chose to disclose.
I stood beside the bedroom window while she spoke. A delivery truck was backing into the alley below, its warning signal echoing between the buildings. I thought about the first time my father had asked me for money. He had sounded frightened in a way I had never heard before. A major customer had delayed payment, two suppliers were threatening to stop deliveries, and the company needed cash to keep operating. I had recently received a substantial professional bonus and believed I could help him survive a temporary crisis.
He had promised to repay me. I remembered that clearly. We sat in his office after most employees had gone home, the overhead lights buzzing faintly, and he explained that the money would be returned once several outstanding contracts were completed. He told me that putting the arrangement in writing would protect us both. I had been relieved by his seriousness. At twenty-seven, I was proud that my father trusted me enough to involve me in something important. I did not yet understand that trust required records and accountability on both sides.
Mara sent a formal request that afternoon. She asked for the original funding agreement, any amendments, documents recording repayment or forgiveness, and records showing how the company had classified my contributions. She also requested copies of materials submitted to the refinancing lender that concerned my financial interests. I reviewed the letter before it went out. It contained no accusations about my father’s motives. It simply identified documents that should exist if his claims were accurate. For once, I did not feel compelled to soften reasonable questions to spare his feelings.
Rachel continued reviewing the company accounts while we waited. She called attention to an unusual pattern in the older statements: several transfers I remembered as loans had been recorded under descriptions that changed over time. Early records treated them as amounts owed to an outside creditor. Later summaries appeared to group some of the same money with owner-related funding. Rachel explained that bookkeeping classifications could change for legitimate reasons, but those changes normally required a documented basis. She wanted to know who authorized them and whether I had agreed.
I asked what difference the classification made. She explained that a genuine loan created an obligation to repay according to its terms, while a gift or certain kinds of capital contribution could be treated differently. If my father had persuaded a lender that money he owed me no longer needed to be repaid, the company’s liabilities would appear smaller. That could improve the appearance of its financial position during refinancing. But changing the description in a spreadsheet did not automatically change the underlying legal obligation. The relevant agreements would determine what had actually occurred.
The explanation unsettled me. I had expected to discover that my father wanted me to guarantee new debt. It had not occurred to me that the refinancing might also depend on redefining money I had already given him. I opened my records and traced the earliest substantial payments. There were bank confirmations, messages promising repayment, and occasional acknowledgments from the company. I had never demanded a rigid schedule because I believed our relationship was secure. Now I understood that my willingness to be patient had created years of uncertainty about what was owed.
Two days later, Madison called. Her voice sounded different from the sharp, defensive tone she had used during the boutique dispute. She said she had spoken with Mara about preserving the refinancing files and wanted me to know that she had not deleted anything. She had provided information about the laptop and the folders she used while helping Dad prepare the application. Mara was arranging an appropriate way for the relevant records to be reviewed without unnecessarily exposing unrelated personal information or confidential company materials.
I thanked Madison for cooperating. She hesitated, then asked whether I believed she had deliberately tried to make me responsible for the loan. I told her I did not know everything she had understood at the time. Her actions mattered, but so did the instructions she had received and the records showing what she actually did. She said Dad had told her that the family had already agreed to support the refinancing. When she questioned whether I needed to sign another document, he said he would handle that part himself. She had believed him.
I asked whether she had questioned the unusual email address. Madison said she noticed that it was slightly different from the address she remembered me using, but Dad told her it belonged to an account used for financial correspondence. She admitted she had never checked with me. Her voice grew strained as she explained that Dad became irritated whenever she asked too many questions. I recognized the feeling. Both of us had spent years learning that his confidence was supposed to end a discussion, even when we did not understand what he wanted.
Then Madison said something I had not expected. She told me that when the refinancing application was being assembled, my father had mentioned an older agreement that would make the lender more comfortable. She did not understand its terms, but she remembered seeing a document with my name on it and a section discussing repayment. Her father had told her the paperwork was being updated to reflect the family’s current arrangement. I asked whether she knew where that document was stored. She said she had seen it in a folder of scanned agreements, but she was no longer certain which version was final.
After the call, I sent Mara a summary of Madison’s recollection. I included the parts she could not remember and resisted the temptation to make her statements more precise than they were. Mara thanked me and said the information could help identify where to look for original records. She also reminded me that Madison should receive independent advice about her own involvement. I agreed. My sister had made choices that harmed me, but I did not want her frightened into accepting blame for decisions she might not have made.
The original documents arrived from my father’s attorney the following Monday. His letter was brief and noticeably formal. It stated that the company was providing copies of certain historical agreements without admitting any wrongdoing or accepting my interpretation of the transactions. Attached were scanned contracts, repayment schedules, equipment documents, and several pages of handwritten notes. I forwarded everything to Mara and Rachel before examining the files myself. My hands were shaking slightly when I opened the first agreement.
There it was: a signed acknowledgment that the company had received a substantial loan from me during its earlier financial crisis. The document identified the principal amount, described the permitted purpose of the advance, and provided for repayment once the company reached specified financial conditions. My signature appeared on the final page, accompanied by my father’s signature in his capacity as company president. I remembered signing it. The moment came back with unexpected clarity, right down to the glass of water he had placed beside the paperwork.
Another agreement recorded a later advance, this one connected to outstanding supplier obligations. Several subsequent documents confirmed additional amounts and modifications to repayment timing. Some of the records were incomplete, and a few transactions I had made over the years were plainly gifts rather than loans. But the central fact was unmistakable: at least part of my financial support had been formally recognized as debt owed to me. My father had repeatedly spoken as though all the money was a daughter’s contribution to her family. His own documents told a more complicated story.
Rachel began reconciling the agreements with the company’s accounting records. She identified amounts that appeared to remain outstanding, subject to verification of repayments, amendments, and other adjustments. The preliminary total was substantial. I did not celebrate it. The thought of recovering money from a business already struggling to pay suppliers and employees frightened me. But knowing that the obligation existed changed how I understood the past. My father had allowed me to continue believing repayment was a vague future kindness when the company had formally acknowledged specific debts.
The most troubling document was attached near the end of the package. It concerned the refinancing application and purported to modify my position as a creditor. According to its wording, I had agreed to subordinate certain repayment rights and release specified claims as part of the proposed financing arrangement. A signature appeared beneath my name. Mara had already warned me to review anything related to the new application carefully. I stared at the page and recognized the familiar shape of the signature from the disputed funding authorization.
I had never signed that modification. I had never agreed to surrender repayment rights, and nobody had explained the proposed arrangement to me. The document was not simply a statement that I would help the company in the future. It appeared to represent my consent to changes affecting money already owed to me. I called Mara immediately. She asked me to identify the document number and confirm that I had never authorized the modification. I answered both questions without hesitation. She said we needed to compare the submitted versions and determine whether the lender had relied on it.
Rachel joined the call a few minutes later. She explained that removing or subordinating a significant obligation could make the company’s financial position look stronger or alter how creditors would be paid. The precise consequences depended on the documents’ enforceability and the refinancing terms. But the apparent purpose was clear enough to warrant investigation. My father had not only represented me as a continuing source of financial support. The application materials also suggested that I had consented to surrender or postpone rights arising from earlier loans.
I sat at my kitchen table after the call, looking at the printed agreements. For years, I had believed I was helping my father recover from temporary difficulty. I had accepted delays because I trusted him to repay what he could when the company improved. Meanwhile, the family’s spending increased, and he became angry whenever I asked questions. The new documents suggested that instead of confronting the unpaid obligations honestly, he had tried to incorporate a supposed waiver into a refinancing package without obtaining my genuine agreement.
That evening, my father called. I answered because I wanted to hear whether he would acknowledge what the documents showed. He began by saying his attorney had provided the records I requested and that there was no reason to continue making trouble. I told him I had reviewed the original loan agreements and the later modification. He said the company had always treated my help as family support. I pointed out that the original documents expressly described portions of it as repayable loans. He replied that I was focusing on technical language rather than understanding.
I asked why the refinancing package contained a document showing that I had agreed to give up repayment rights. His tone hardened immediately. He said the company could not move forward while old family loans remained on its books and that the refinancing had been designed to benefit everyone. I asked why he had not simply explained the proposed changes and requested my signature. He said he knew I would complicate the arrangement by demanding guarantees and independent advice. I told him that was exactly why my consent mattered.
He was silent for a moment. Then he said he had never intended to cheat me. He believed the company would eventually recover, and once it did, he would take care of me as he had always promised. I looked at the agreements spread across my table. His explanation assumed that good intentions could replace informed permission. I told him that promising to help me later did not give him the right to erase obligations today. He said I had become obsessed with money. I replied that I was concerned about honesty.
For the first time, he asked me directly what I wanted. I told him I wanted the lender to receive accurate records, the unauthorized documents withdrawn, and the legitimate outstanding obligations acknowledged. I did not demand immediate repayment that would destroy the business. I wanted a realistic plan based on what the company could actually afford. He said that would be humiliating. I answered that concealing obligations and using disputed authorizations created far greater risks than admitting the company needed restructuring.
He accused me of siding with outsiders against my family. I reminded him that the people reviewing the matter were doing so because he had refused to answer basic questions. He could still provide records and cooperate. He could still protect employees by making decisions based on accurate financial information. But I would not sign away my rights or guarantee new debt simply to preserve the appearance that everything was fine. He ended the call without saying goodbye.
I remained at the table long after the screen went dark. The apartment smelled faintly of coffee, and the radiator clicked against the wall. I could remember my father lifting me onto his shoulders at a company picnic when I was six. I remembered him teaching me to ride a bicycle and helping me prepare for my first job interview. Those memories were real. So were the documents in front of me. I had spent weeks trying to decide which version of him I should believe, as though one had to cancel the other.
The next morning, Mara sent a formal notice disputing the apparent modification of my repayment rights. She requested that the lender refrain from relying on the document until its authenticity and authorization could be established. Rachel updated her financial analysis to distinguish documented historical loans from other contributions and to show how the proposed modification affected the refinancing figures. The report was careful about amounts still requiring reconciliation. We were not pretending to know more than the records supported.
Later that afternoon, Mara called with a final piece of information. The lender’s copy of the refinancing packet contained both the new funding authorization and the document purporting to change my creditor rights. My father’s company had submitted them together as part of the evidence supporting its application. The problem was larger than a single scanned signature appearing on one form. Two separate representations about my consent had been incorporated into the proposed transaction, and neither had been knowingly authorized by me.
I asked Mara what happened next. She said we had enough evidence to supplement the existing complaint and request a fuller review of how the documents had been created and submitted. A qualified examination of the signatures and electronic records would be important. Depending on the results, the matter could involve serious questions about false representations and unauthorized execution of financial documents. She would not predict a legal finding before the investigation was complete. I appreciated the caution, even as I felt the weight of what we had discovered.
That evening, I signed the supplemental statement Mara had prepared. It described the original loans, identified the disputed modification, and confirmed that I had not agreed to relinquish repayment rights or undertake the new funding commitment. I read every page before signing. When I finished, I placed the pen beside the folder and looked at the two disputed signatures on my screen. My father had spent years reminding me that family loyalty meant trusting him. Now the records showed exactly why trust without accountability had become dangerous.
END PART 9
PART 10 TITLE: As the Investigation Reached the Construction Company, I Faced the Choice Between Saving My Father’s Business and Protecting My Own Future
The first employee to contact me was a foreman named Daniel Mercer. I had known him since I was a teenager, when he supervised a crew renovating an elementary school near our neighborhood. He called on a Wednesday afternoon, sounding uncomfortable about reaching out directly. He said rumors about the refinancing had spread through the company, and several employees were worried about their next paychecks. My father had told them outside interference was delaying the funds needed to keep projects moving. Daniel wanted to know whether there was anything I could clarify.
I leaned against the window beside my desk and listened. Daniel had worked for the company for almost twenty years. His wife had recently reduced her hours to care for an elderly parent, and his family depended on his wages. I remembered him laughing at company picnics and teaching younger workers to handle difficult tasks without embarrassing them. Hearing the worry in his voice made the conflict feel different from the legal correspondence filling my inbox. These were not figures on a spreadsheet. They were people whose lives could be disrupted by decisions they had not made.
I told Daniel that I could not discuss confidential financial information or speculate about the lender’s review. I did explain that I had not authorized certain commitments attributed to me and that those discrepancies were being examined. He was quiet for a moment, then asked whether I intended to shut the company down. I told him I had no such authority and no desire to see employees lose their jobs. My concern was that the business needed a financial plan based on reliable resources rather than promises made without permission.
Daniel sighed. He said most of the crew understood the company was struggling, but nobody knew how serious the problem had become. Suppliers were beginning to request tighter payment terms, and some equipment repairs had been postponed. He had noticed my father becoming increasingly short-tempered with managers who raised concerns. I could picture that easily. My father had always responded to uncertainty by tightening his control. When people asked questions, he treated them as signs of disloyalty rather than opportunities to solve problems before they grew.
After ending the call, I contacted Rachel. I told her about Daniel’s concerns and asked whether there was a legitimate way to help employees without returning to the open-ended financial arrangement I had just escaped. Rachel said the first step was determining the company’s actual cash position and immediate obligations. A business experiencing a liquidity crisis sometimes had options beyond family borrowing, including negotiating payment schedules, collecting receivables, reducing nonessential expenditures, or obtaining independently underwritten financing. But those choices required management cooperation and accurate records.
I asked whether I should offer a temporary loan restricted to payroll. Rachel did not dismiss the idea, but she wanted me to understand the risks. Money intended for one purpose could become entangled with other obligations unless appropriate safeguards existed. A business that could not support its operating costs might need more than a short-term payment. She also reminded me that I already had substantial unresolved exposure through earlier loans. Providing additional funds without a credible restructuring plan could worsen my position without protecting employees for long.
The discussion left me conflicted. I had built my career helping businesses understand difficult financial choices. I knew how to distinguish a short-term cash shortage from a structural problem. Yet when the business belonged to my father, every calculation carried memories that made objectivity difficult. I wanted Daniel and the other employees to receive their wages. I wanted customers’ projects completed safely and suppliers paid fairly. I also wanted to stop being the person who absorbed every financial consequence while having no authority over the decisions creating them.
Rachel suggested a different approach. If my father was willing, the company could appoint an independent turnaround adviser to review its obligations and develop a realistic operating plan. That would not guarantee survival, but it would replace optimistic assumptions with verifiable figures. She offered to recommend qualified professionals who had worked with construction firms. I asked whether she would be willing to help arrange an initial discussion. She agreed, provided everyone understood that any engagement would require proper authorization from the company.
I sent my father a written proposal the following morning. I explained that I was willing to facilitate an introduction to an independent restructuring specialist, but I would not provide another unsecured transfer or validate documents I had not signed. The specialist could review cash flow, outstanding contracts, supplier arrangements, and financing options. I also suggested that the company consider separating financial oversight from my father’s personal decisions while the document dispute was being examined. The message was practical and deliberately free of accusations.
His response arrived just before lunch. He wrote that he did not need outsiders telling him how to run a business he had built from nothing. He said the company would be fine if I stopped interfering with the refinancing. He also claimed that employees were suffering because of my actions. I stared at the message while the office around me continued its ordinary rhythm of ringing phones and quiet conversations. I had offered a way to examine the problem without demanding control. He had rejected it because accepting help would mean allowing someone to see the books.
I forwarded his reply to Mara and returned to my client work. I was beginning to understand that I could not rescue someone from consequences while allowing that person to control every condition of the rescue. My father wanted money without oversight, loyalty without questions, and forgiveness without acknowledgment. Those were not terms I could accept. I could offer a constructive option. I could not force him to choose it.
That afternoon, Madison sent Mara additional information about the files she had used during the refinancing application. The records included copies of drafts and correspondence relating to the documents bearing my name. Mara told me she would review their provenance and determine what could properly be provided to the investigators. She also emphasized that Madison should seek her own legal advice before making detailed statements about potentially unauthorized documents. I agreed. The situation had moved beyond family accusations, and careless attempts to explain could create more confusion.
Two days later, Mara called me into her office. She had received material indicating that the disputed authorization had been assembled from earlier records rather than executed through a new signing process. The preliminary electronic evidence was consistent with the possibility that an image of my signature had been inserted into the document. It was not yet a complete forensic conclusion, and Mara did not present it as one. But the source files and surrounding correspondence made the explanation of an innocent clerical misunderstanding increasingly difficult to sustain.
I sat across from her, watching sunlight move across the edge of the conference table. She showed me a copy of a message from the preparation period in which my father referred to using existing signed documents while the refinancing paperwork was being completed. Another message discussed the need to keep the application moving despite outstanding questions about my agreement. Neither contained a direct admission that he had intentionally forged my signature. Together, however, they suggested that the company had proceeded without obtaining fresh authorization from me.
I asked what Madison had said about those messages. Mara explained that Madison recalled being instructed to assemble the packet from old files. She maintained that she had believed my father was responsible for obtaining any necessary consent. She had not contacted me because he told her the arrangements were already settled. Mara was careful not to endorse her account as complete. The documents and electronic records would need independent review, and responsibility for each step remained a matter for investigation.
The distinction mattered because I did not want my anger to determine anyone’s guilt. Madison had spent years expecting me to pay for things she could not afford, and her behavior at the boutique was indefensible. But that did not mean she had knowingly participated in every part of the refinancing problem. I wanted her to take responsibility for what she had actually done, not become a convenient explanation for my father’s decisions. The same principle applied to him. He deserved an accurate investigation, even if the truth ultimately proved painful.
That weekend, my mother came to my apartment carrying a small paper bag. She had called beforehand, and I agreed to speak with her for an hour. She looked thinner than when I last saw her, and her coat hung loosely from her shoulders. I made tea while she sat at the kitchen table. She took a folded envelope from her handbag and placed it beside her cup. Inside were several receipts and account statements relating to personal expenses she and my father had incurred while the company was struggling.
She told me she had been examining their finances for the first time in years. She had discovered how many expenses were supported by transfers, credit arrangements, or payments routed through accounts she had never questioned. She did not fully understand which transactions were business expenses and which were personal, but she could see that their lifestyle had become dependent on money they could not consistently afford. Her voice cracked when she admitted that she had preferred not to ask questions because she enjoyed the comfort those arrangements provided.
I listened while she described the house, the cars, the vacations, and the endless effort to maintain an appearance of success. She had convinced herself that my father’s business was always about to recover and that my contributions were temporary acts of generosity. Whenever I raised concerns, she interpreted them as criticism of the family’s achievements. She said she understood now that I had been trying to tell them something important long before the argument at dinner.
I asked why she had continued shopping after I canceled the card. My mother looked down at her hands. She admitted that she had expected me to reverse the decision because I always had before. She had told herself the boutiques were part of their ordinary life and that I would eventually forgive another purchase. When the payment was declined, she felt humiliated. Only later did she begin to understand that the embarrassment came from trying to spend money she no longer had permission to use.
She apologized for standing beside my father while he threw me out. The words were quiet and hesitant. She said she had been afraid that contradicting him would make the argument worse, but that fear did not excuse leaving me alone. I looked toward the damaged suitcase, still tucked beside my bedroom wardrobe because I had not bothered to replace it. I had imagined hearing that apology many times. When it finally came, I did not feel the immediate relief I expected. The hurt had become too complicated to vanish in one conversation.
I told her I appreciated the apology, but I needed changes rather than promises. She nodded and said she had begun reviewing her own spending. She planned to return or sell several expensive items, including the cream-colored handbag, and had started discussing a more realistic household budget. I did not congratulate her or offer to manage the process. It was her responsibility. For the first time, she seemed to understand that I could care about her without taking control of every financial problem she faced.
Before leaving, my mother asked whether the company would survive. I told her I did not know. Rachel believed there were legitimate business assets and contracts, but the existing financial approach was unsustainable. An independent review might identify a workable path. My mother said my father was frightened of losing the respect of his employees and relatives. I told her he had to decide whether preserving an image mattered more than preserving the business itself. She nodded, though I was not sure she was ready to repeat those words to him.
The following Monday, Rachel received confirmation that the lender was continuing its review of the disputed application and that the accounting concerns remained unresolved. Mara had also received acknowledgment of our supplemental statement and supporting evidence from the investigators handling the complaint. I asked whether any formal findings had been made. She said not yet. The available records raised serious questions, but the process needed to establish precisely what had been submitted, who authorized it, and whether the lender had relied on false representations.
I returned to my office and spent the afternoon preparing a client presentation. Working on someone else’s financial forecast felt almost soothing. Numbers were not free from judgment, but they offered a framework for examining assumptions. At five, I checked my phone and found three missed calls from my father. I listened to the first voicemail. He sounded exhausted rather than furious. He said suppliers were demanding answers, the refinancing remained delayed, and he had begun to realize how little room the company had left.
In the second message, he asked whether the restructuring specialist I had mentioned was still available. I replayed it because I had not expected him to reconsider. The third voicemail contained no request for money. He simply said he wanted to discuss how the business might continue without relying on the funding arrangement that had caused so much trouble. I called Mara before responding. She advised me to keep the professional and personal issues separate and to ensure that any restructuring discussion involved qualified independent advisers.
I sent my father a short reply with the specialist’s contact information and explained that any engagement would need to be arranged directly by the company. I would not negotiate on his behalf or guarantee the outcome. Several hours later, he confirmed that he had scheduled an introductory meeting. The acknowledgment contained no apology, but it was the first concrete step he had taken toward addressing the company’s finances without demanding that I solve them through another transfer.
That night, Madison called to tell me she had moved several personal subscriptions and shopping accounts onto payment methods she controlled. She had also returned merchandise she could not afford. She said the experience had been humiliating, then stopped herself and admitted that the embarrassment was less important than the debt she had accumulated. I listened without offering rescue. She asked whether we could eventually speak as sisters rather than adversaries. I told her that depended on whether we could build a relationship that did not revolve around what I paid for.
I went to bed with a strange mixture of relief and apprehension. My father had finally agreed to seek independent financial advice. My mother had begun acknowledging her own role in the family’s spending. Madison was confronting consequences she had avoided for years. None of those changes erased the disputed documents or the harm already done. But they suggested that the family might begin to function without treating me as its permanent financial safeguard. The question was whether those changes would survive when the full cost of the past became clear.
END PART 10
PART 11 TITLE: When My Father Finally Opened His Books, the Numbers Explained Why He Had Been So Desperate to Keep Me Silent
The restructuring specialist’s name was Thomas Reed, and the first thing he told my father was that he could not repair a business using figures nobody trusted. Rachel repeated that sentence to me after their initial meeting, unable to conceal a little admiration. Thomas had spent nearly twenty years helping privately owned companies through difficult financial periods. He was not interested in preserving my father’s reputation or proving my suspicions correct. His responsibility was to establish the business’s actual condition and determine whether a credible recovery plan could be developed.
My father had agreed to give Thomas access to the company’s books, although not without objections. He wanted the engagement limited to immediate cash-flow problems and initially resisted a broader examination of owner withdrawals, intercompany transactions, and historical financing obligations. Thomas explained that the restrictions would make any conclusions unreliable. According to Rachel, the conversation became uncomfortable before my father reluctantly agreed. I pictured him sitting behind his office desk, surrounded by the certificates and photographs he had collected over decades, discovering that a professional adviser would not simply accept his assurances.
I was not present at the meeting. Mara had recommended keeping some distance while my father’s company resolved its operational issues. My personal financial claims and the disputed refinancing documents remained separate matters. If Thomas needed information about the original loans, he could obtain it through appropriate channels. I appreciated the boundary, even though I found myself wanting updates. The business had occupied so much of my adult life that stepping away from its daily emergencies required deliberate effort. Sometimes I reached for my phone before remembering that a supplier’s problem was no longer automatically mine to solve.
Three days later, Thomas requested a reconciliation of the company’s outstanding obligations. Rachel assisted with the historical transactions involving me, while the company’s accounting staff assembled current liabilities and receivables. The review showed a business with genuine revenue potential but serious weaknesses in financial discipline. Certain projects had been priced too optimistically, payments from customers were slower than anticipated, and operating expenses had continued rising during periods of declining cash reserves. The company also carried obligations whose repayment terms had been repeatedly postponed rather than resolved.
The personal expenditures were especially difficult for my father to explain. Some payments recorded as business expenses appeared to benefit the household or activities unrelated to construction. Thomas requested invoices, authorizations, and supporting records before determining how they should be treated. In several instances, the company lacked adequate documentation. Rachel told me that incomplete bookkeeping did not automatically establish intentional misconduct, but it prevented anyone from producing a dependable financial picture. My father’s habit of making informal decisions had become a substantial obstacle to the recovery he wanted.
My mother called on a Thursday evening after returning from a meeting with a financial adviser of her own. She sounded subdued. She had learned that several household expenses she considered ordinary were far beyond what she and my father could reasonably support from dependable income. The house, cars, insurance, maintenance, and discretionary spending created a monthly burden that left almost no room for unexpected costs. For years, my assistance had concealed that imbalance. Without it, the truth was becoming impossible to ignore.
She told me she had arranged to sell the cream-colored handbag. I looked at the place on my kitchen table where I had first reviewed the twelve-thousand-dollar charge. The handbag had become a symbol of everything that went wrong between us, but I did not want its sale treated as an extraordinary sacrifice made for my benefit. It had been purchased with money she had no right to spend without asking. Selling it was one step toward correcting an irresponsible decision, not proof that the entire problem had been solved.
My mother seemed to understand. She said she had also canceled several memberships, postponed planned travel, and begun reviewing the cost of keeping the larger vehicle. Her financial adviser had explained that changing the SUV financing would require a formal arrangement with the lender, and she was exploring available options. I told her I was glad she was taking the obligations seriously. She asked whether I thought she was a terrible mother. I said I thought she had made choices that hurt me and that I needed to see sustained change before our relationship could recover.
She cried quietly, but she did not argue. Then she said something that surprised me. She admitted that she had encouraged my father to ask me for help during the earliest company crisis because she knew I had recently received a bonus. At the time, she believed he would repay me quickly. When the business continued struggling, she began treating my money as an extension of the household’s resources. She said she had gradually stopped distinguishing between asking for help and assuming it would always be available. I appreciated her willingness to name the change.
That weekend, Madison invited me to meet at a small café near my apartment. She arrived wearing jeans, a plain coat, and shoes I had seen before. There was no expensive handbag on her arm. We ordered coffee and sat near the window, where condensation blurred the view of passing cars. For several minutes, we talked about ordinary things. She mentioned a job interview and complained about the difficulty of explaining gaps in her work history. I listened, cautiously grateful that she was discussing something other than shopping.
Eventually, Madison took a folder from her bag. She said she had spoken with an attorney about her involvement in the refinancing paperwork and had decided to cooperate fully with the appropriate review. She could not discuss everything while the matter was being examined, but she wanted me to know she had preserved the relevant electronic files and explained the instructions she remembered receiving. Her attorney had advised her not to speculate or accept responsibility for actions she could not verify. I told her that was sensible.
She looked embarrassed. “I should have asked you,” she said. “About the documents. About the email. About all of it.” I agreed. She went on to say that she had spent years assuming Dad knew what he was doing because he always spoke with such certainty. When he told her the refinancing paperwork was routine, she accepted it. When he said I had already agreed, she did not question him. And when she wanted expensive purchases, she persuaded herself that my earlier generosity meant I would never seriously refuse.
I asked why she had been so angry at the boutique when the card failed. She stirred her coffee until the spoon struck the cup. She admitted that she had been embarrassed in front of people whose opinions mattered to her. She had already imagined carrying the merchandise home, posting photographs, and receiving compliments. When the payment was refused, she felt exposed. Rather than acknowledge that she could not afford the purchases, she blamed me for making her appear foolish. Her explanation was uncomfortable but believable.
I told Madison that I had often helped because I wanted us to remain close. I remembered paying for a trip she wanted to take after a painful breakup and helping with rent when she struggled to find work. Those were choices I did not regret. What hurt was discovering that she seemed to value my ability to pay more than my company. Madison looked directly at me and said she had begun to understand the difference. She did not ask for money or suggest that one apology should erase everything.
We left the café after almost two hours. At the corner, Madison hugged me briefly and asked whether we might meet again. I said yes, provided we could keep financial requests out of our conversations for a while. She nodded. Watching her walk toward the bus stop, I felt something I had not expected: sadness for the years in which we had treated purchases as a substitute for knowing one another. I had paid for experiences we rarely discussed afterward. She had accepted the gifts without understanding what they cost me beyond money.
On Monday, Mara called with an update concerning the disputed signatures. A preliminary technical examination of the available electronic documents supported the conclusion that the signature images on the newer authorizations had been reproduced from an earlier signed record rather than freshly executed. The examiner’s analysis identified corresponding image characteristics that would be highly unusual in separate handwritten signatures. Mara emphasized that the work still needed to be evaluated alongside the original files, submission records, and witness accounts before responsibility could be assigned.
The lender’s internal review had also identified discrepancies in the verification information used for the refinancing application. The unfamiliar email address was not associated with my ordinary communications, and the application records did not support the claim that I had personally confirmed the new commitments. Additional records suggested that responses sent through the questionable address had been handled from systems connected with the company’s application preparation. Those facts did not identify a particular individual conclusively, but they undermined the representation that the lender had obtained independent confirmation from me.
I listened as Mara explained the implications. The lender had informed the company that the existing refinancing package could not proceed in its submitted form. Any future application would require corrected financial information and properly verified authorizations. The institution was also reviewing whether the disputed materials warranted further action under its internal procedures. Mara would not predict whether formal charges or civil claims would follow. What mattered immediately was that no new financing obligation could be imposed on me merely through the disputed documents.
I felt a release of tension so sudden that I had to sit down. For weeks, I had carried the fear that a financial commitment might be created in my name without my consent and that I would spend years untangling it. Mara reminded me that there could still be administrative or legal work ahead, especially concerning the historical loans and the unauthorized documents. But the lender’s decision meant the disputed application was no longer moving forward on the assumption that my signature and approval were genuine.
Later that afternoon, Thomas contacted me through Mara with a proposal concerning the company’s legitimate obligations. He had completed an initial restructuring assessment and believed the business might continue operating if it reduced unnecessary expenses, negotiated revised payment schedules, and imposed stricter financial controls. Several creditors were willing to discuss arrangements rather than demand immediate liquidation. The company would need to reduce certain activities and possibly dispose of underused assets. It would also need to acknowledge the documented loans owed to me.
Thomas proposed a written repayment arrangement that reflected the company’s realistic cash capacity. It would not return my money quickly. Some obligations might be paid over several years, and the schedule would depend on enforceable agreements and continuing business performance. He asked whether I would consider discussing such an arrangement through counsel. I told Mara I was willing to review it, provided I was not asked to forgive debts through unauthorized documents or guarantee additional borrowing. A genuine restructuring had to recognize reality rather than conceal it.
My father attended the next meeting with Thomas, Mara, and the company’s own attorney. I participated remotely for the portion concerning my claims. The discussion was orderly, almost painfully so. My father acknowledged the original loan agreements and agreed that the disputed refinancing documents could not be treated as evidence of my authorization. He did not admit intentionally falsifying anything. His attorney stated that the company would cooperate with the continuing review. It was a limited acknowledgment, but after weeks of angry denials, the change mattered.
Thomas explained that the company could not continue relying on informal family funding. He proposed regular reporting, independent review of significant expenditures, and a realistic schedule for creditors. My father objected to several restrictions, particularly those involving personal access to company funds. Thomas answered that lenders and suppliers were unlikely to regain confidence without reliable controls. Eventually, my father agreed to consider the measures as part of a broader recovery plan. I watched him struggle with the realization that authority came with responsibilities he could no longer delegate to family loyalty.
After the meeting, my father requested a private conversation through Mara. I agreed to speak with him by telephone, with the understanding that financial negotiations would remain with our advisers. When he called, his voice sounded tired. He said the business had reached a difficult point and that he wished the situation had never become so public. I told him I wished we had addressed the problems honestly years earlier. He replied that he had been afraid of losing everything he built. I asked whether that fear explained why he stopped asking for my permission.
For a long moment, he said nothing. Then he admitted that he had assumed I would always help. He said he believed the company would eventually recover and that any temporary arrangements could be corrected later. I asked about the copied signature. He answered that the refinancing paperwork had been handled badly and that he should have ensured my consent was obtained before anything was submitted. I told him the issue was more serious than bad paperwork. A document had represented my agreement when I had given none.
His breathing became audible over the telephone. He said he understood that the documents should not have been used. He did not offer a complete explanation of who made each decision, and I did not attempt to extract one from him in a private conversation. The formal review would need to establish the facts. But he did say something I had never heard from him before. “I was wrong to assume your money was available just because you were my daughter.”
I looked toward the damaged suitcase standing near my wardrobe. I had imagined those words while lying awake after the argument at his house. Now they sounded smaller than I expected. They did not repair the years of pressure or the damage caused by the disputed documents. Yet they were the first acknowledgment that his expectations had crossed a boundary. I told him I needed more than an admission about money. He had disowned me because I asked questions, and he had continued accusing me after evidence showed those questions were justified.
He said he knew. Then he asked whether we could meet without attorneys, spreadsheets, or relatives. I told him I would consider it after the restructuring agreement was documented and the financial issues were no longer being used to pressure me. He accepted that answer without arguing. When we ended the call, I remained seated for several minutes. I was beginning to see the difference between a father who felt sorry because his plans failed and a father willing to acknowledge the harm he had caused. I did not yet know which one he intended to become.
A week later, Thomas delivered an updated restructuring proposal. The company would pursue negotiated creditor arrangements, reduce discretionary spending, establish stronger financial oversight, and address my documented loans through a formal repayment schedule. My father would no longer have unrestricted discretion over certain significant expenditures while the recovery plan remained in place. The proposal could not guarantee success, but it offered a credible alternative to repeated emergency transfers. I asked Mara to review every provision before I considered signing anything.
That evening, my mother called to tell me the cream-colored handbag had been sold. She did not mention how much she received until I asked, and even then she sounded more embarrassed than proud. She said the money would be used toward legitimate household obligations rather than another luxury purchase. She also told me she had stopped asking my father to maintain appearances they could no longer afford. I listened and realized that, for the first time, she was describing changes she had made without asking me to finance or approve them.
Before ending the call, she asked whether I would come to dinner once the legal matters were more settled. I told her I could not promise the family would return to what it had been. She said she understood. Then she asked whether we might build something different. I looked around my small apartment, at the books, the plants, and the furniture I had chosen without consulting anyone. I told her that was the only kind of relationship I was interested in now. She said she would try.
END PART 11
PART 12 TITLE: When My Father Finally Asked What It Would Take to Bring Me Home, I Gave Him an Answer He Had Never Expected
Three months after my father threw my suitcase down the marble staircase, I received a letter confirming that the disputed refinancing application had been withdrawn. The lender would not proceed using the authorizations submitted in my name, and its records reflected that I had not agreed to the proposed funding commitment or the purported modification of my repayment rights. Additional review of the documents and their preparation was continuing through the appropriate channels. I read the letter twice, then placed it on my kitchen table beside the original agreements.
The letter did not erase what happened. It did not return the years I had spent covering expenses or settle every question about who prepared the disputed documents. But it confirmed something essential: the financial commitments attributed to me would not be accepted simply because my father believed I should have agreed. My signature, my credit, and my money belonged to me. For a long time, I had understood that principle professionally while allowing my family to behave as though it did not apply at home.
Mara called later that morning to explain the remaining issues. The evidence concerning the copied signature and inaccurate verification address had been preserved and reviewed, and the relevant complaint remained subject to further assessment. No final criminal finding had been issued, and she cautioned me against treating the lender’s decision as a legal judgment about every person’s responsibility. The financial protection I had sought was largely in place, but the broader consequences would follow their own process. I told her I understood. I wanted accountability grounded in evidence, not punishment based on anger.
The company’s restructuring arrangements were progressing more slowly. Thomas had negotiated revised terms with several suppliers and helped management prioritize payments essential to ongoing projects. Some equipment was sold, discretionary spending was reduced, and certain expansion plans were abandoned. The business did not emerge untouched. It lost opportunities my father had once considered certain, and a few positions were eliminated through a difficult reorganization. But the company continued operating, and most employees remained at work under a more realistic financial plan.
Daniel Mercer called after the first month of the revised arrangements. He told me that payroll had arrived on schedule and that managers were receiving clearer information about upcoming projects. He sounded relieved, although he acknowledged that everyone remained cautious. My father was spending more time reviewing job costs with supervisors and less time making promises about contracts that had not yet been finalized. Daniel said the atmosphere was different. Nobody believed the company was suddenly free of trouble, but at least the employees had a better understanding of what was happening.
I thanked him for the update and told him the people doing the actual work deserved that clarity. After we ended the call, I sat quietly for a while. During the earliest crisis, my fear for employees like Daniel had made me willing to transfer money without asking enough questions. This time, they were receiving a more durable form of help: management decisions based on the company’s actual resources. I wished my father had accepted that approach years earlier, before his need to appear successful led him into increasingly desperate arrangements.
The agreement concerning my historical loans took several rounds of negotiation. Mara and the company’s attorney reviewed the original documents, reconciled the amounts supported by records, and distinguished genuine loans from gifts and informal assistance. I did not attempt to recover every dinner, vacation, or personal expense I had paid over the years. Those choices had been mine, however regrettable some became afterward. What mattered was that obligations formally acknowledged by the company would no longer disappear beneath vague references to family generosity.
The resulting repayment schedule was cautious. It provided for payments over time, with reporting requirements and protections appropriate to the company’s condition. The plan did not guarantee I would recover every outstanding dollar, and Mara made certain I understood the risks. But it recognized the documented debt rather than pretending I had voluntarily surrendered my rights. I accepted the arrangement because it was based on verified information and realistic capacity, not because my father demanded another sacrifice to protect his pride.
The company also adopted financial controls that my father would once have rejected immediately. Significant expenditures required documented approval, and the restructuring adviser would monitor the recovery plan for an agreed period. Personal expenses could no longer be casually mixed with company transactions. My father remained involved in construction operations, where his experience was valuable, but he no longer exercised unrestricted control over financial decisions. The change was difficult for him. I understood that. I also believed it was necessary.
My mother adjusted more visibly than anyone expected. She sold several luxury possessions, reduced household spending, and began handling ordinary purchases through accounts she controlled herself. The expensive SUV remained a complicated obligation, but she worked with the lender to address it rather than expecting me to make the payments indefinitely. She no longer sent photographs of things she wanted followed by reminders that I had always helped before. Instead, our conversations gradually returned to books, meals, old memories, and the small events of our daily lives.
The change was awkward at first. Sometimes she mentioned an expense and stopped suddenly, as though afraid I would interpret any financial complaint as a request for money. I told her she could speak honestly about difficulties without expecting me to solve them. We were learning a distinction that should have been obvious long ago. A mother could tell her daughter that a car repair was frustrating. A daughter could listen sympathetically. Neither conversation had to end with a transfer from my bank account.
Madison had found work with a small events company. The position was not glamorous, and the salary was lower than she had imagined earning when she first began describing her career ambitions. She complained about early mornings and difficult customers, but she also sounded proud when she told me about a project she had completed successfully. For the first time, she was beginning to understand what it meant to plan purchases around money she had actually earned. She still made mistakes, but she was learning to correct them herself.
One Saturday, she invited me to lunch and insisted on paying. We ate at a modest restaurant with scratched wooden tables and a menu printed on thick paper. When the bill arrived, she reached for it before I could move. I almost protested out of habit. Then I realized she wanted to do something generous without turning it into a performance. She paid, left a tip, and asked whether I wanted to walk with her afterward. We spent the afternoon wandering through a park, talking about work and people we knew.
It was the first outing with Madison in years that did not include shopping. I noticed how much more interesting she became when she stopped describing herself through the things she wanted to own. She was funny, observant, and surprisingly thoughtful about her new responsibilities. She admitted that she had been frightened during the refinancing investigation, particularly when she realized how carelessly she had handled documents involving my name. She was still cooperating through appropriate channels and knew the review might have consequences. I told her that facing those consequences honestly mattered more than pretending they did not exist.
My own life changed in quieter ways. I began saving for a larger apartment again. I replaced the broken suitcase, although I kept the damaged one in a storage closet for a while because throwing it away felt strangely difficult. I took weekends off without checking whether my father needed help with an invoice. I accepted invitations from friends I had neglected. Sometimes I still felt anxious when my phone rang unexpectedly. Years of family emergencies had trained me to assume that every call might end with someone asking for money.
The anxiety gradually lessened. I learned that a missed call from my mother could simply mean she wanted to share a recipe. Madison might send a photograph because something made her laugh, not because she expected me to purchase it. My father called less frequently than either of them. When he did, our conversations were brief and cautious. He asked about work and occasionally mentioned a construction project. We avoided the disputed documents because those matters remained subject to formal review. There was still too much between us to pretend ordinary conversation could resolve everything.
Then, one Thursday afternoon, he asked whether I would come to the house for dinner. He said my mother and Madison would be there, but he wanted to speak with me privately first. I asked what he needed to discuss. He replied that he owed me an apology and did not want to deliver it over the telephone. I was silent long enough that he asked whether I had heard him. I said yes. Then I told him I would come, provided nobody expected the visit to change our financial agreements.
He said he understood. I wanted to believe him, but I had learned not to treat a promise as proof of change. I called Mara to confirm that attending a family dinner would not interfere with any pending financial arrangements or formal review. She advised me to keep legal matters within their proper channels and to avoid making new financial commitments during the visit. I assured her I had no intention of doing that. The reason I was going was personal. For once, I wanted to see whether my father could speak to me as his daughter without treating money as the subject beneath every sentence.
I arrived just before six. The driveway looked different. My mother’s luxury vehicle was gone, and a smaller car stood near the garage. The landscaping remained neat, but the elaborate seasonal decorations she once commissioned were absent. Inside, the house smelled of roasted chicken and rosemary. My mother opened the door and greeted me with a hesitant smile. She did not ask whether I had brought anything. She simply took my coat and told me my father was waiting in the living room.
He stood near the fireplace, where he had defended himself during the emergency family meeting. His hair had grown noticeably grayer, and he looked tired. For a moment, neither of us spoke. Then he gestured toward the sofa and asked me to sit. I remained standing until he sat first. The gesture was small, but I needed to feel that I had chosen to enter the room rather than been summoned there. My father noticed. He looked down at his hands and waited.
He began by saying that he had spent months thinking about the night he threw me out. He said he remembered my suitcase striking the stairs and the expression on my face when he told me I was no longer his daughter. He had convinced himself that I was threatening the family’s security by refusing to provide more money. He understood now that I had been trying to explain a problem he did not want to hear. His voice was rough, but he continued without asking me to comfort him.
He apologized for using our relationship as a way to pressure me. He acknowledged that he had made financial promises without obtaining my agreement and that the refinancing documents should never have been submitted as evidence of my consent. He said the company had become so dependent on optimistic assumptions that he stopped distinguishing between what he hoped would happen and what he had the right to promise. He did not attempt to settle the legal questions himself. He said he would continue cooperating with the formal review.
I listened carefully. Part of me wanted to embrace him immediately. Another part remembered his furious messages and the way he had accused me of trying to steal his business when I asked about my own signature. I told him I appreciated the apology, but I needed him to understand that the damage did not begin with the refinancing. It began years earlier, when he started treating my willingness to help as evidence that I had no right to refuse. He nodded slowly and said he had been ashamed to admit how much he relied on me.
Then he asked what he could do to make me feel welcome in the family again. The question brought me back to the foyer on that Friday evening, two weeks before the failed boutique purchase. I could see the broken suitcase wheel, Madison leaning over the railing, and my mother holding the handbag I had unknowingly paid for. I remembered my father’s words and how desperately I had wanted him to take them back. I had spent months wondering whether our relationship could survive without the money that seemed to hold it together.
I looked at him and answered quietly. “You told me I wasn’t your daughter anymore. But everyone still expected my credit card, my savings, and my name on your paperwork. I need you to understand something, Dad. You can’t throw your daughter out and expect her wallet to stay behind.”
My father stared at me. From the doorway, I heard my mother stop moving. Madison had entered the room without either of us noticing, and she stood beside her with her hands clasped in front of her. Nobody spoke for several seconds. I had not raised my voice or prepared a dramatic accusation. I had simply described the contradiction that had governed our lives for years. My father looked toward the staircase, then lowered his eyes.
Finally, he said, “You’re right.” The words were barely audible. He told me he had mistaken my generosity for an obligation and my independence for disrespect. He had been proud of my success when it benefited the family, but resentful whenever it gave me the confidence to disagree with him. He said that was not the kind of father he had intended to become. I told him intentions mattered less than what he did next. He nodded and said he knew.
My mother came into the room and sat beside him. She apologized again for remaining silent during the argument and for continuing to ask about money afterward. Madison admitted that she had treated access to my accounts as something she was entitled to rather than something I had voluntarily provided. None of them asked me to forgive everything immediately. I was grateful for that. I told them I wanted a relationship in which we could disagree without threats, make our own financial decisions, and speak honestly even when the truth was uncomfortable.
We had dinner together. The conversation was hesitant at first, interrupted by silences that everyone noticed. My mother served roasted vegetables and apologized unnecessarily because one dish was slightly overcooked. Madison described a difficult event she had helped organize at work. My father asked about a project I was managing and listened when I explained it. He did not dismiss my profession or suggest that working with financial records was easy. It was a small change, but after years of being valued primarily for what my work earned, it mattered.
The legal and financial consequences continued beyond that evening. The company remained responsible for its legitimate debts and the conditions of its restructuring plan. The lender’s disputed application was not reinstated, and no new guarantee from me was created. The complaint concerning the documents remained subject to the proper review process, with no promise that every question would produce a quick or satisfying result. My father continued cooperating through counsel. I did not withdraw truthful statements or conceal evidence in exchange for reconciliation.
Our family relationships recovered more slowly than any of us wanted. There were awkward holidays and conversations in which old habits briefly returned. Occasionally, my mother began suggesting a purchase before remembering that she needed to make the decision within her own budget. Madison sometimes complained about being unable to afford something extravagant, then laughed at herself and changed the subject. My father still struggled when I disagreed with him. But he stopped treating disagreement as a reason to threaten our relationship.
Several months later, I received the first payment under the company’s documented repayment arrangement. The amount was modest compared with what remained outstanding. I checked that it matched the agreed schedule and filed the confirmation with my records. I did not call my father to thank him for paying a legitimate obligation. Nor did I use the payment as proof that everything had been repaired. It was simply one installment in a process that required consistency. That ordinary, documented payment meant more than the countless assurances he had once given me.
I eventually moved into a brighter apartment with a small study overlooking a quiet courtyard. On moving day, Madison arrived carrying boxes, and my mother brought sandwiches she had made herself. My father came later with a toolbox and helped repair a loose shelf. Nobody mentioned money. Nobody asked me to cover an unexpected bill. We worked until evening, arguing mildly about where the furniture should go and laughing when Madison assembled a chair incorrectly. It was the first time in years that a family gathering left me feeling supported rather than depleted.
When everyone had gone, I stood in the new living room among half-open boxes and looked out at the courtyard. My phone lay on the kitchen counter, quiet. The cards connected to my old family spending arrangements remained canceled or securely replaced, and the disputed financial commitments had been addressed through formal processes. I still loved my parents and my sister. I also understood that loving them did not require surrendering my independence. The family I had tried so hard to preserve had changed, but the relationships that remained had a chance to become more honest.
I thought once more about the night my father ordered me out. At the time, I believed losing his approval might mean losing my family completely. What I discovered was that remaining under the old conditions would have cost me something equally important: the ability to direct my own life. Leaving did not solve everything. It forced questions into the open that we had avoided for years. Some answers were painful, and some consequences would take a long time to resolve. But none of us could continue pretending that love and financial access were the same thing.
I turned off the lights, leaving only the lamp beside my reading chair. On the table lay a photograph from my childhood, showing my father holding my hand outside one of his earliest construction projects. I kept it because that memory was still part of my life, even after everything that followed. I no longer needed to deny the good years to acknowledge the harm. And I no longer needed to buy my place in anyone’s home. The next time I visited my family, I would arrive as a daughter who had chosen to come, not as the person expected to pay for being allowed inside.
END PART 12
